
From raw accounting data to investor KPIs: a manual reporting framework
A manual investor KPI framework: align SPV inputs, document mappings and roll-up rules, calculate metrics separately, and reconcile outputs to evidence.
Integration update, 20 October 2026: Clarity Ledger now connects Xero, QuickBooks Online and FreeAgent. GBP Xero examples below remain valid. Check current provider and currency eligibility; planning, KPI and pack-preparation tasks described as manual remain separate workflows.
Clarity Ledger does not calculate or publish the investor KPIs described here. Maintain this pipeline and its evidence separately; it is not an enabled KPI dashboard, transaction drill-through, forecasting or investor-pack feature.
Investor reporting should feel simple:
- What is the portfolio doing?
- What changed this month?
- What is the risk (cash, covenants, refinancing, leasing)?
- What returns are we generating-and how confident are we?
But if your portfolio sits across 10/25/100 SPVs, the reality is that the "truth" is fragmented. Each SPV has its own chart of accounts, timing, bank accounts, and edge cases-so creating consistent investor KPIs becomes a monthly rebuild.
This post describes a finance-team framework for deriving and reviewing investor KPIs from accounting and operational inputs. It is a manual or separately configured process.
Why investor KPIs break in multi-SPV portfolios
Most reporting issues are not "accounting errors." They are meaning errors:
- "Maintenance" means different things across SPVs
- capex vs opex gets coded inconsistently
- cash is reported without splitting restricted/trapped balances
- NOI definitions drift between packs
- portfolio totals are built in spreadsheets, not systems
- operational drivers (occupancy, arrears) live outside the GL
So two problems appear:
- The numbers are hard to consolidate consistently
- The commentary is hard to justify confidently
The fix is not "more reporting." It is a standardised reporting logic layer above the raw accounting data.
Core principle: one reconciled base, many views
Start with a simple design goal:
A portfolio KPI should always be traceable back to SPV-level source data-without reinterpreting it every month.
Keep three layers separate:
- Source data (what the accounting system says)
- Reporting meaning (what it means in your portfolio model)
- Investor outputs (how that meaning is presented: KPIs, packs, commentary)
The pipeline: Raw -> Normalise -> Map -> Consolidate -> Calculate -> Explain
Step 1: Ingest the raw SPV accounting data
Begin at SPV level, because that is where legal entities, bank accounts, and debt typically sit.
Inputs to collect and review separately:
- Trial balance (and/or ledger detail) per SPV
- Bank balances (ideally reconciled)
- Debt schedules (balances, rates, maturities; covenant definitions where applicable)
- Optional but high-value operational inputs: occupancy, arrears, capex pipeline
Why this matters: AI, dashboards, and packs are only as trustworthy as the base inputs. If cash is not tied to the bank, your "net debt" and runway story will be wrong.
Step 2: Normalise messy reality without rewriting your bookkeeping
A manual reporting model can map accounts without changing each SPV's bookkeeping structure.
In the external reporting model, align:
- naming conventions (so reporting is readable)
- time periods and cutoffs (so comparisons are meaningful)
- key classifications (so NOI and capex do not drift)
This is where you reduce "spreadsheet glue work" that happens every month.
Step 3: Map each SPV chart of accounts into a standard reporting structure
This is the heart of consistent portfolio reporting.
Definition
A mapping links SPV accounts -> standard portfolio reporting lines (for example, "Property Maintenance", "Utilities", "Management Fees", "Financing Costs").
Common mistake
Teams try to standardise every SPV's bookkeeping chart first (slow), or they map "just for this month's pack" (not reusable).
Best-practice reporting
- A stable standard reporting structure
- A mapping table per SPV that can be reused every month
- Version control on mapping changes (so trends do not silently break)
This is how you get apples-to-apples reporting across dozens of entities.
Step 4: Consolidate across SPVs with explicit rules
After mapping, reconcile the roll-up and document ownership and manual adjustments before relying on totals.
What consolidation means in management reporting
- Roll up performance across SPVs into portfolio totals
- Support both portfolio-level and SPV-level views
- Handle ownership rules (100% view plus investor share, or pro-rata-defined explicitly)
Common mistakes
- Portfolio totals built via manual exports and copy-paste without retained reconciliation evidence
- Mixing entities that are not closed yet with final entities (no completeness visibility)
- Ignoring intercompany, then wondering why balances do not make sense
Best-practice reporting
- A close completeness flag ("which SPVs are final vs estimated")
- Clear ownership basis used consistently
- Intercompany treated explicitly (eliminate when reliable, otherwise isolate transparently)
Step 5: Calculate investor KPIs from the standardised reporting layer
Once the portfolio view is consistent, KPIs become definition-driven instead of "prepared-by" driven.
Below are illustrative definitions for separately calculated KPIs; agree the reporting basis with the reviewer.
KPI logic examples
1) NOI
Definition (typical)
NOI = Revenue - Operating Expenses (excluding financing, tax, and usually excluding capex)
Common mistakes
- capex creeping into operating costs (or vice versa)
- one-offs treated inconsistently month to month
- NOI definition changing between internal and investor reporting without a bridge
Best-practice reporting
- A published NOI definition (what is in / what is out)
- A consistent classification rule set enforced via mapping
- Optional "NOI (underlying)" view with one-offs clearly tagged
2) Cash that is actually usable
Definition (minimum viable)
Split cash into:
- Unrestricted cash (usable)
- Restricted cash (DSRA, escrow, tenant deposits, etc.)
- (Often) Trapped cash (technically cash, but not realistically transferable due to covenants/structure)
Common mistakes
- reporting "total cash" as if it is deployable
- subtracting restricted cash when calculating net debt (or worse: ignoring restrictions entirely)
Best-practice reporting
- Portfolio cash always shown with restrictions split
- Cash drill-down: portfolio -> SPV -> bank account (and restrictions label)
3) Net debt and gearing / LTV
Definition (typical)
- Net debt = Total debt - usable cash
- LTV (%) = (Debt / Asset value) x 100 (valuation basis and date must be disclosed)
Common mistakes
- using net debt based on total cash (ignores restrictions)
- presenting LTV without the valuation date (or mixing valuation dates across assets)
- showing only portfolio averages when covenants bite at facility/SPV level
Best-practice reporting
- Net debt uses only usable cash
- LTV always labelled with valuation basis/date
- Covenant ratios/headroom tracked at facility/SPV level first, then rolled up
4) Capex: spent vs committed (the cash-trough predictor)
Definition
- Spent capex = cash outflow already incurred
- Committed capex = approved/contracted pipeline not yet spent
Common mistakes
- reporting only what was spent this month, missing what is contractually coming next
- mixing refurb programmes into OpEx in some SPVs and Capex in others
Best-practice reporting
- Capex dashboard shows spent + committed + remaining budget
- Timing view for the next 4-8 weeks (what hits cash soon)
- Consistent capex vs opex rule set (enforced via mappings)
5) Distributions and capital repayment
Definition (example)
- Distributions as a percentage of initial equity = (Cumulative cash distributions / Initial equity invested) x 100
- Track additional contributions and any repayment of contributed capital separately in an equity bridge.
Total distributions can include income or gains; this percentage does not establish how much invested principal has been repaid. If there have been further contributions, disclose them rather than keeping an initial-only denominator without explanation. For a since-inception distributions-to-paid-in-capital multiple, the CFA Institute GIPS glossary uses total since-inception distributions divided by total since-inception paid-in capital. This example does not imply GIPS compliance.
Common mistakes
- mixing realised cash returns and valuation-driven changes without separating them
- presenting return metrics without linking to cash constraints (cash may be trapped in SPVs)
Best-practice reporting
- Clear split between cash returned vs unrealised movement
- Distribution capacity shown alongside liquidity and covenant constraints
Step 6: Explain the numbers with controlled, traceable commentary
Once KPIs are grounded in mapped categories and definitions, commentary becomes safer and more useful.
This is where modern finance teams increasingly want AI support-but only in the right place in the stack:
- AI can draft "what changed" and highlight exceptions
- Humans approve
- Each statement should be traceable back to mapped reporting lines and underlying numbers
That is how you get speed without giving up control.
The trust layer: what makes the logic audit-friendly and repeatable
A reviewed KPI workflow should retain evidence for:
- Drill-down: KPI -> reporting line -> SPV -> account -> source
- Definition clarity: NOI, cash, net debt, LTV, occupancy all explicitly defined
- Change control: mapping and definition changes are tracked (so trends remain meaningful)
- Completeness visibility: which SPVs are included, which are estimated, which are missing
Clarity Ledger's available foundation is saved historical GBP Xero P&L, balance sheet and trial balance reports after successful sync, with Source/Standard views and user-reviewed mappings. KPI calculations, operational data, adjustments, forecasting, scenarios and AI commentary in this guide are separate workflows.
What this enables beyond reporting
Once the reporting logic is stable, it compounds:
- A one-stop portfolio view across SPVs
- Standardised roll-ups for investor packs
- FP&A: budgets, forecasts, cash planning
- Scenario planning: rates, occupancy shifts, refurb programmes
- Automated narrative generation grounded in your mapped accounts and controls
Closing thought: investor KPIs are a logic problem, not a formatting problem
If investor reporting feels painful, it is usually because your portfolio's "meaning layer" is missing:
- mappings to standardise categories
- definitions to stabilise KPIs
- clean inputs and reconciliation discipline to keep the base trustworthy
Get those foundations right, and the path from raw accounting data to investor KPIs becomes repeatable-and scalable.
More operations insights for real estate finance teams.
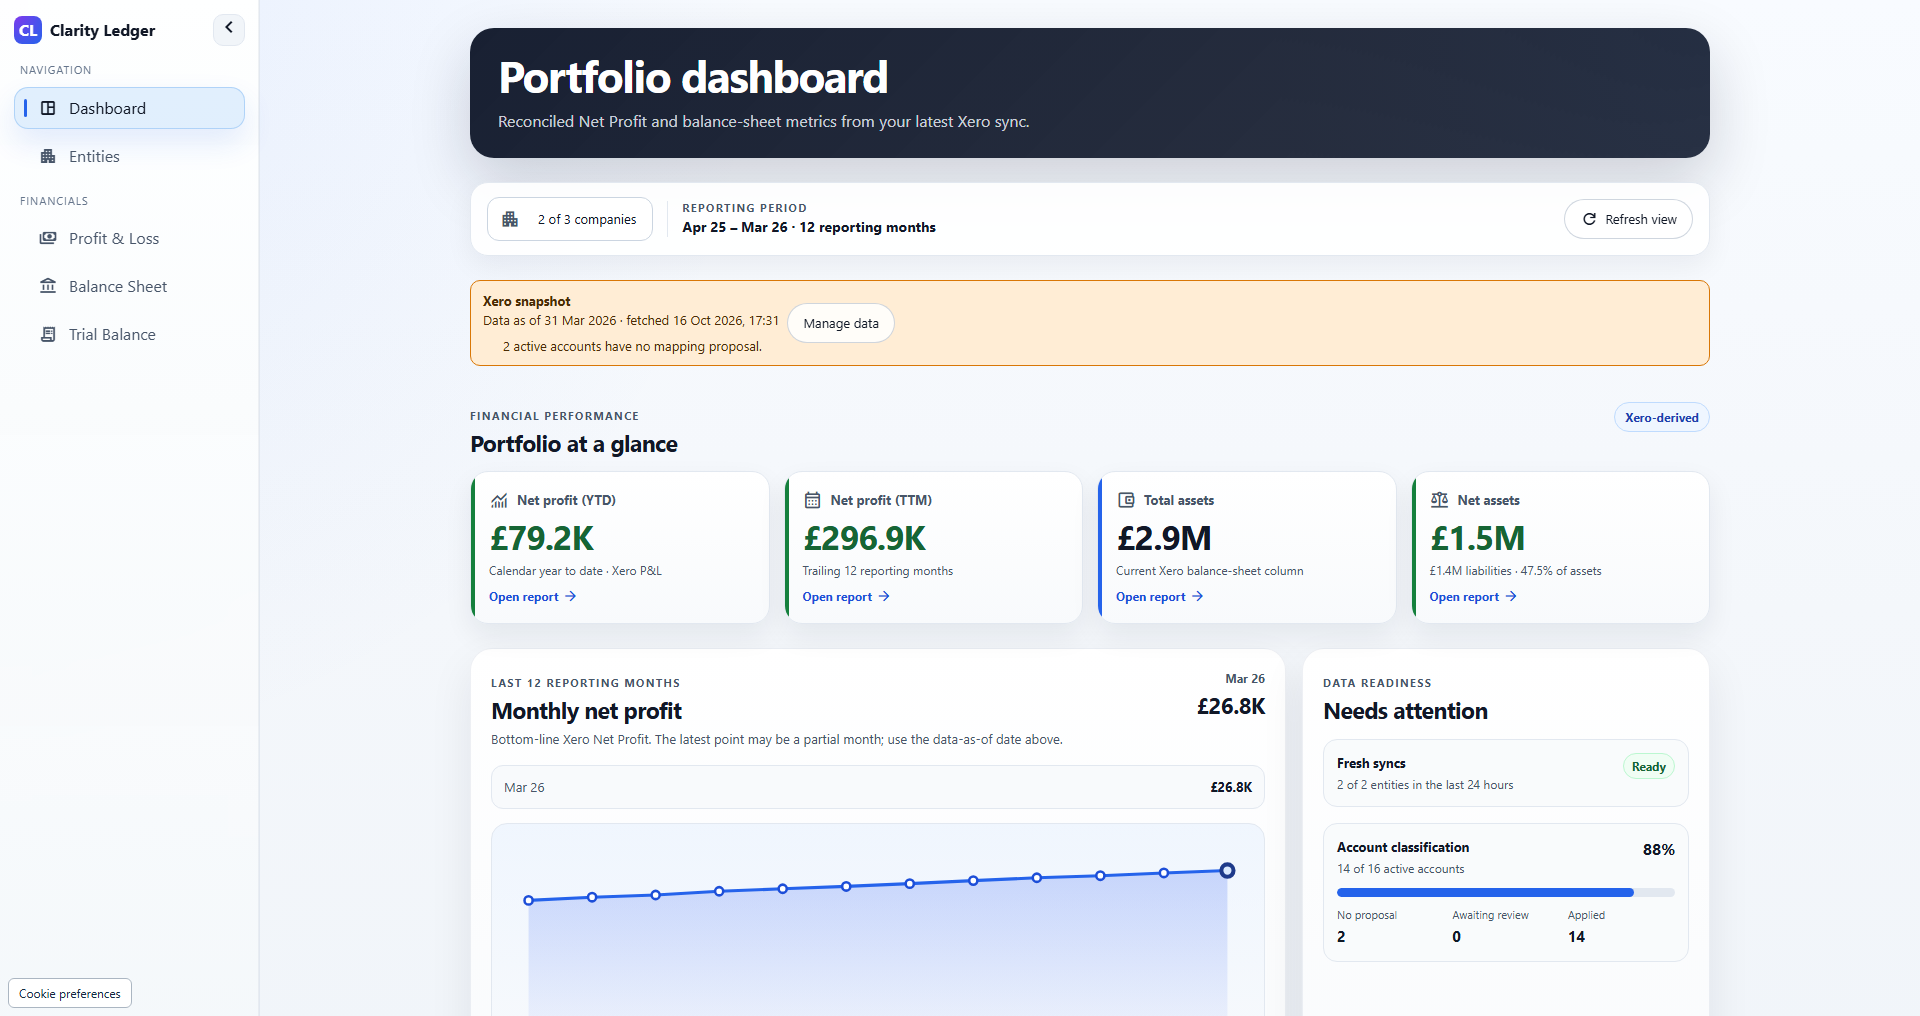
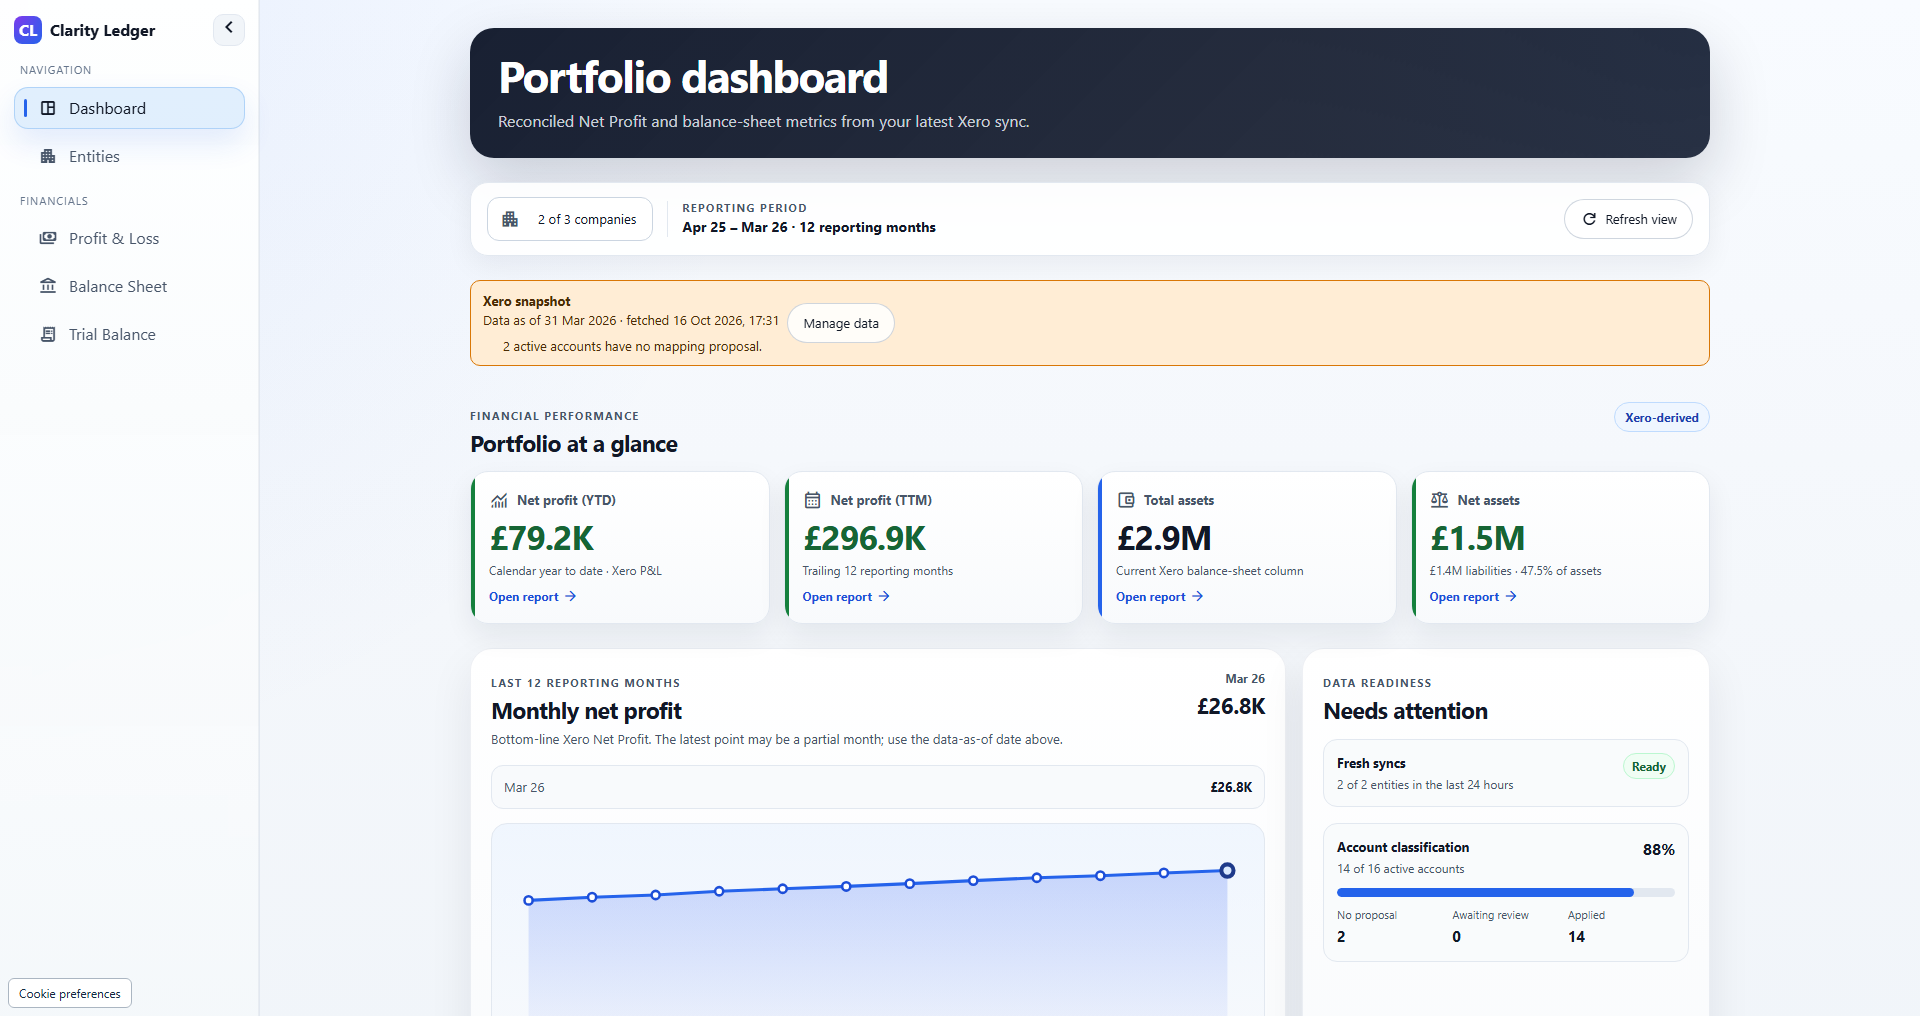
Actual Clarity Ledger portfolio dashboard · Illustrative demo data
Release notes that matter: what changed and why it helps finance teams
A finance-grade release note template that answers what changed, who is affected, why it matters, what to do, and how to validate-so multi-entity teams keep reconciliations, definitions, and trust intact.
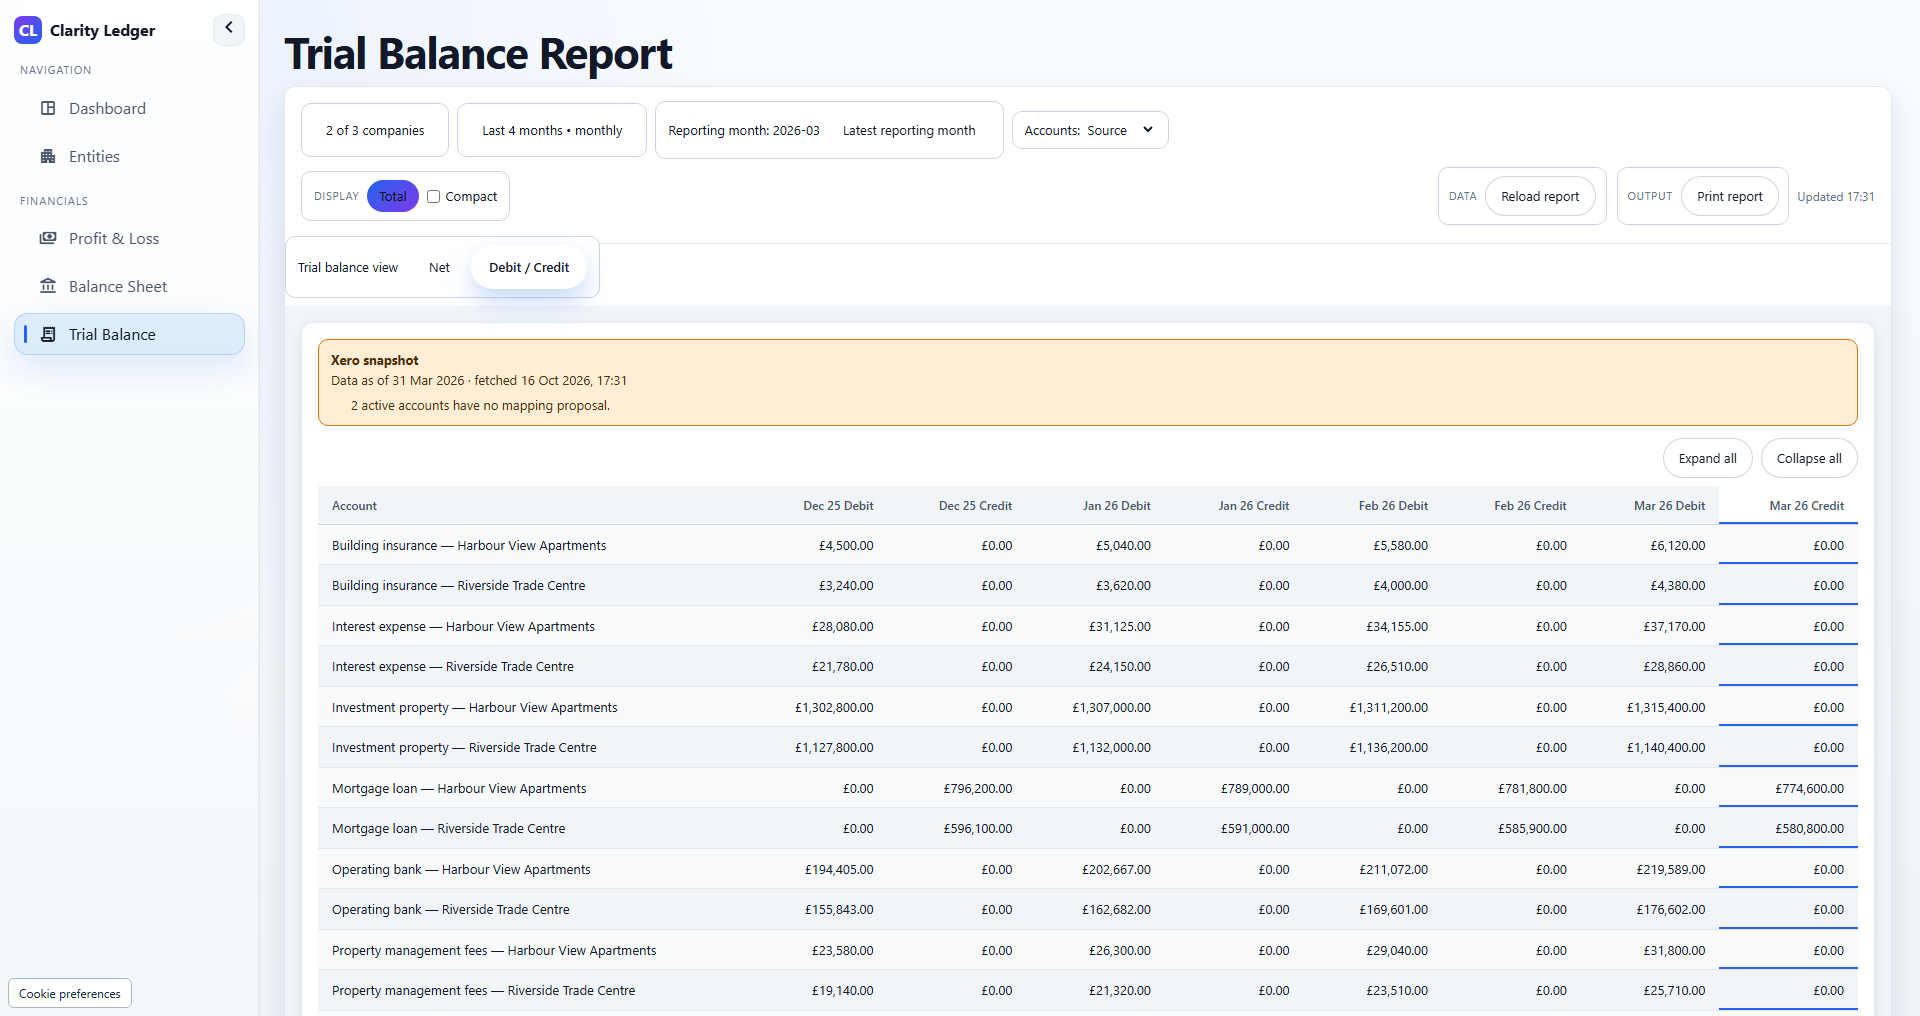
Actual Clarity Ledger trial balance report · Illustrative demo data
A month-end close checklist for property SPVs
Practical, evidence-based close routine for rent-led SPVs-cash, rent roll tie-outs, service charge, capex vs opex, debt and covenants-plus a downloadable PDF checklist you can use this month.
Actual Clarity Ledger portfolio dashboard · Illustrative demo data
Portfolio dashboard design principles for property investors
A finance-team design guide to portfolio dashboards, KPI definitions, source evidence, scenario models and investor commentary, with the current Clarity Ledger reporting scope explained.
Ready for portfolio-grade reporting?
Review Xero, QuickBooks Online and FreeAgent companies in one dashboard, with saved financial reports and account mappings you apply. A 21-day trial is available once per eligible portfolio.