
Commentary that builds confidence: "what changed this month" done right
A repeatable, SPV-ready commentary framework: headline, drivers, why, cash/constraints, actions-built on consistent definitions and drillable rollups so monthly reporting earns trust.
Integration update, 20 October 2026: Clarity Ledger now connects Xero, QuickBooks Online and FreeAgent. GBP Xero examples below remain valid. Check current provider and currency eligibility; planning, KPI and pack-preparation tasks described as manual remain separate workflows.
The templates below are for manually prepared commentary. Calculate any KPI or forecast in a separate reviewed schedule; Clarity Ledger does not automatically produce the narrative, cash outlook or covenant assessment.
Because the fastest way to lose trust is not a bad month-it is unclear reporting.
Most portfolio reports fail in the same place: the numbers might be accurate, but the commentary does not explain them.
You have probably seen it (or written it under time pressure):
- "Performance was broadly in line with expectations."
- "Costs were higher due to one-offs."
- "Occupancy softened slightly."
- "We remain optimistic."
That kind of commentary does not build confidence-it creates questions. And when investors and boards start asking "Can we trust this?", your month-end becomes a reconciliation exercise instead of a decision process.
Good commentary does one job exceptionally well:
It turns raw outputs into a clear, consistent story of what changed, why it changed, what it means, and what you are doing next.
Here is how to do it properly-every month, without reinventing the wheel.
What "good" looks like
Confidence-building commentary has five qualities:
- Specific (numbers, not vibes)
- Comparable (same definitions month-to-month and across SPVs)
- Attributable (changes explained by clear drivers)
- Actionable (next steps, owners, timing)
- Drillable (you can back it up quickly when questioned)
If your commentary is missing any of those, it may read well-but it will not stand up in a tough meeting.
Why "what changed this month" is so hard in SPV portfolios
In multi-asset, multi-SPV portfolios, commentary breaks down because:
- Definitions drift (NOI, capex, finance costs mean different things across entities)
- Charts of accounts are not aligned, so the rollups change depending on how you map them
- One-off reclasses distort trends
- You cannot explain variances without opening each SPV
- "Portfolio" numbers do not reconcile cleanly to entity-level reports
So commentary becomes cautious, vague, or overloaded with caveats-because the team cannot confidently trace the story.
The fix is not "better writing." The fix is a repeatable framework plus consistent underlying rollups.
A repeatable structure for the monthly explanation
If you only adopt one change, adopt this order:
1) Headline (one sentence)
Start with the conclusion, not the backstory.
Example:
"Illustrative example: NOI fell by £82k MoM, attributed in the supporting schedule to a temporary occupancy dip in two assets and higher property operating costs. The cash outlook and covenant position require separate forecasts and facility checks."
2) What changed (top 3 drivers with numbers)
Show the largest material changes and reconcile them to the reported movement.
Example drivers:
- Occupancy / rent / collections
- Opex step-changes or one-offs
- Capex phasing
- Debt service / rates
- Refinancing timing
3) Why it changed (root cause)
Tie the driver to reality: lease events, downtime, contractor timing, rates, seasonality-whatever is true.
4) So what (cash + constraints)
Translate into the outcomes stakeholders care about:
- minimum cash and when
- covenant headroom / DSCR/ICR proxy
- distributions timing (if applicable)
- concentration risk (which SPVs/assets drove it)
5) Now what (actions, owners, timing)
Close with actions that connect directly to the drivers.
The "bridge" method: make variance explanation effortless
The easiest way to write credible commentary is to build a simple bridge from last month -> this month, using consistent driver buckets.
A practical real estate bridge might be:
-
Income
- occupancy/voids
- rent changes (uplifts, renewals, reversion)
- collections/arrears
-
Costs
- controllable opex (repairs, utilities, PM fees)
- non-controllable/step costs (insurance, rates)
-
Capital
- capex phasing (planned vs committed vs actual)
-
Finance
- interest rate movement
- balance change (amortisation/drawdowns)
- fees/hedging
-
Other
- accounting reclasses / prior period adjustments (always call these out explicitly)
This turns "explaining the month" into a repeatable template-rather than a blank page.
Focus commentary on the metrics that actually drive decisions
A common mistake is writing commentary on everything.
Instead, anchor commentary on the handful of portfolio metrics that drive decisions and confidence:
The "must cover" set (for most SPV portfolios)
- NOI (and what is driving it)
- Occupancy (and whether it is temporary vs structural)
- Cash balance + cash runway (minimum cash and timing)
- Capex (actual vs committed vs forecast; timing risk)
- Debt service and rates (interest cost movement; refinance timing)
- Exceptions/outliers (assets/SPVs that deviated materially)
If a report includes these consistently, stakeholders stop asking "what happened?" and start asking "what do we do?"
The biggest confidence killer: hidden definition changes
If you want commentary that builds trust, be ruthless about consistency:
- NOI should be calculated the same way every month
- capex vs opex classification should follow a portfolio policy
- one-off reclasses should be separated from underlying performance
- rollups should reconcile back to SPV financials with a clear audit trail
When definitions change silently, the story becomes untrustworthy-no matter how well it is written.
Tip: add a small "definition changes / reclasses" box every month:
- what changed
- where
- impact (-)
- whether it is one-off or ongoing
This single habit can dramatically reduce investor friction.
"What changed" templates you can copy/paste
Template A: Portfolio-level monthly commentary (short)
Headline: [Portfolio NOI/Cash] was [up/down] £[X] MoM.
Drivers: The change was primarily driven by (1) [Driver 1, £X], (2) [Driver 2, £Y], and (3) [Driver 3, £Z].
Context: [Operational explanation: voids/refurb downtime/rate movement/one-offs].
Cash and constraints: Minimum cash over the next [90/180] days is forecast at £[X] in [Month], with [no / manageable / elevated] covenant pressure ([DSCR/ICR] lowest at [X] in [Month]).
Actions: We are (1) [Action], (2) [Action], (3) [Action], expected to improve [metric] by £[X] by [Month].
Template B: Asset/SPV exception note (use for outliers)
Exception: [Asset/SPV] NOI down £[X] MoM due to [void/refurb downtime/cost spike].
What has changed: [Specific event].
Expected duration: [1-3 months / ongoing].
Mitigation: [Actions], with target recovery by [Month].
Watch-outs: [Risk and trigger].
Use leading indicators to sound "in control" (not reactive)
Investors trust teams that manage forward risk, not just report historical variance.
Add one short "leading indicators" section:
- units in refurb / downtime pipeline
- lease expiries in next 90/180 days
- arrears trend / collections rate
- contractor programme slippage
- rate exposure / hedge cover
- refinancing milestones
This shifts the tone from "here is what happened" to "here is what we are watching and managing."
A simple commentary checklist (before you hit send)
Use these checks before publication:
Clarity
- Is there a one-sentence headline with the key outcome?
- Are the top 3 drivers quantified?
Consistency
- Do the numbers reconcile to SPV-level reporting?
- Were any definitions/reclasses disclosed explicitly?
Decision usefulness
- Did you translate impact into cash runway and constraints?
- Did you name actions, owners, and timing?
Defensibility
- Could you drill down quickly if questioned?
- Are exceptions/outliers called out, not buried?
If you can tick these off, your commentary will feel credible even in a bad month.
Prepare commentary from reviewed reports and operational evidence
Reconcile historical figures first, then add separately maintained rent, occupancy, capex, debt and forecast schedules. A named reviewer should approve the explanation and any forward-looking assumptions.
Clarity Ledger supports selected GBP-base Xero companies, saved historical P&L, balance sheet and trial balance reports after successful sync, and user-reviewed mappings between Source and Standard views. AI narrative, forecasting, scenarios and investor-pack generation are not enabled. See the current reporting workflow.
More operations insights for real estate finance teams.
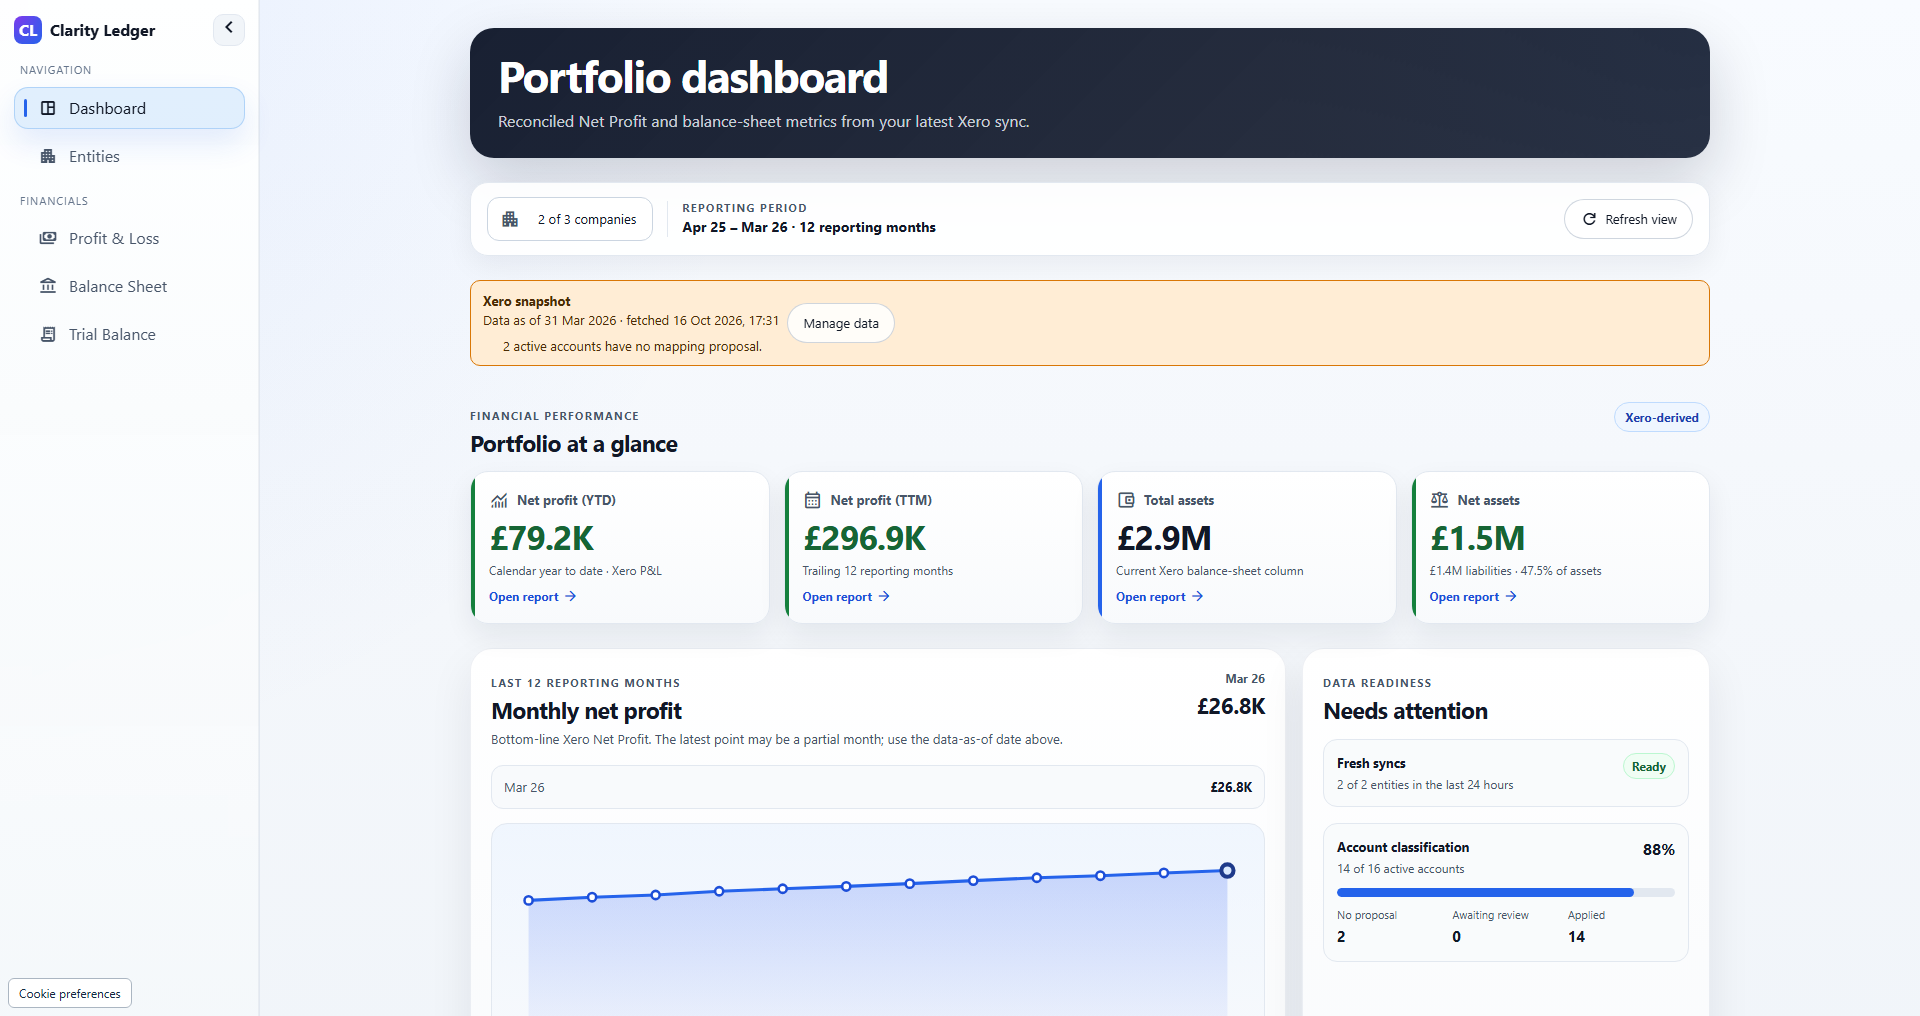
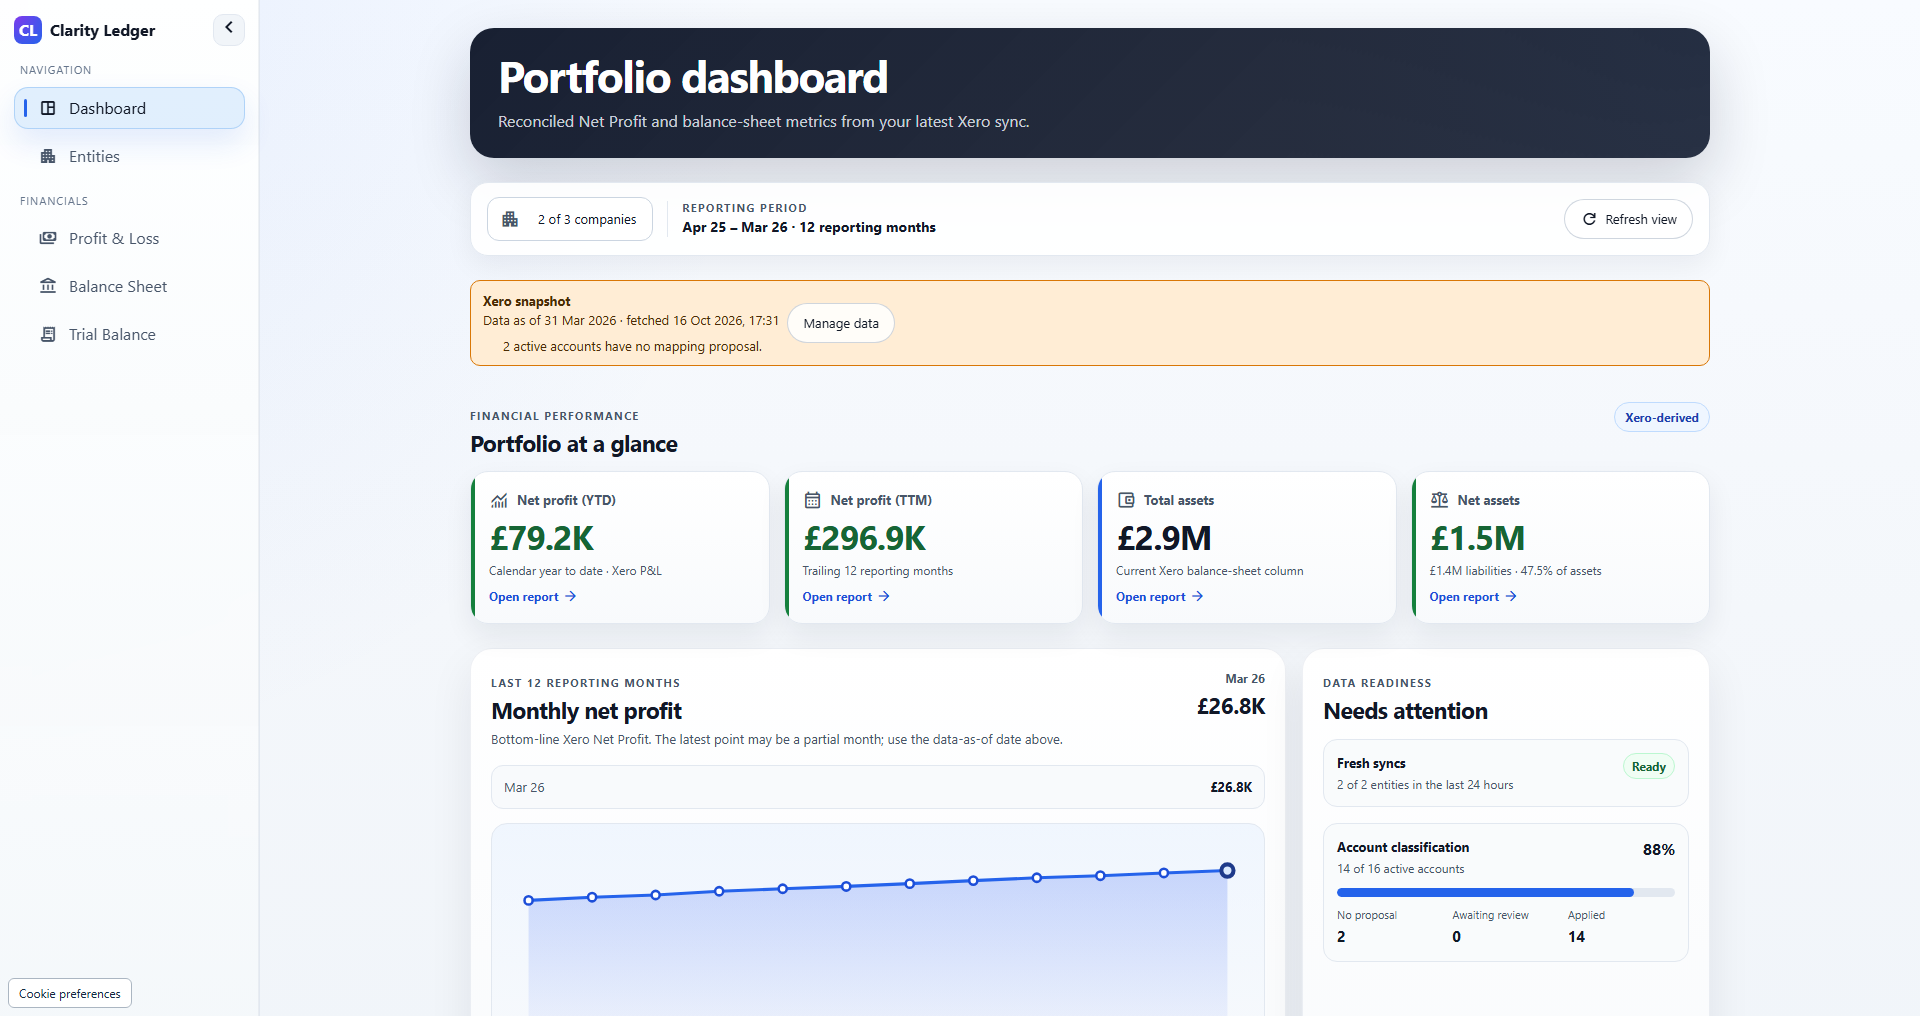
Actual Clarity Ledger portfolio dashboard · Illustrative demo data
Release notes that matter: what changed and why it helps finance teams
A finance-grade release note template that answers what changed, who is affected, why it matters, what to do, and how to validate-so multi-entity teams keep reconciliations, definitions, and trust intact.
Actual Clarity Ledger portfolio dashboard · Illustrative demo data
From raw accounting data to investor KPIs: a manual reporting framework
A manual investor KPI framework: align SPV inputs, document mappings and roll-up rules, calculate metrics separately, and reconcile outputs to evidence.
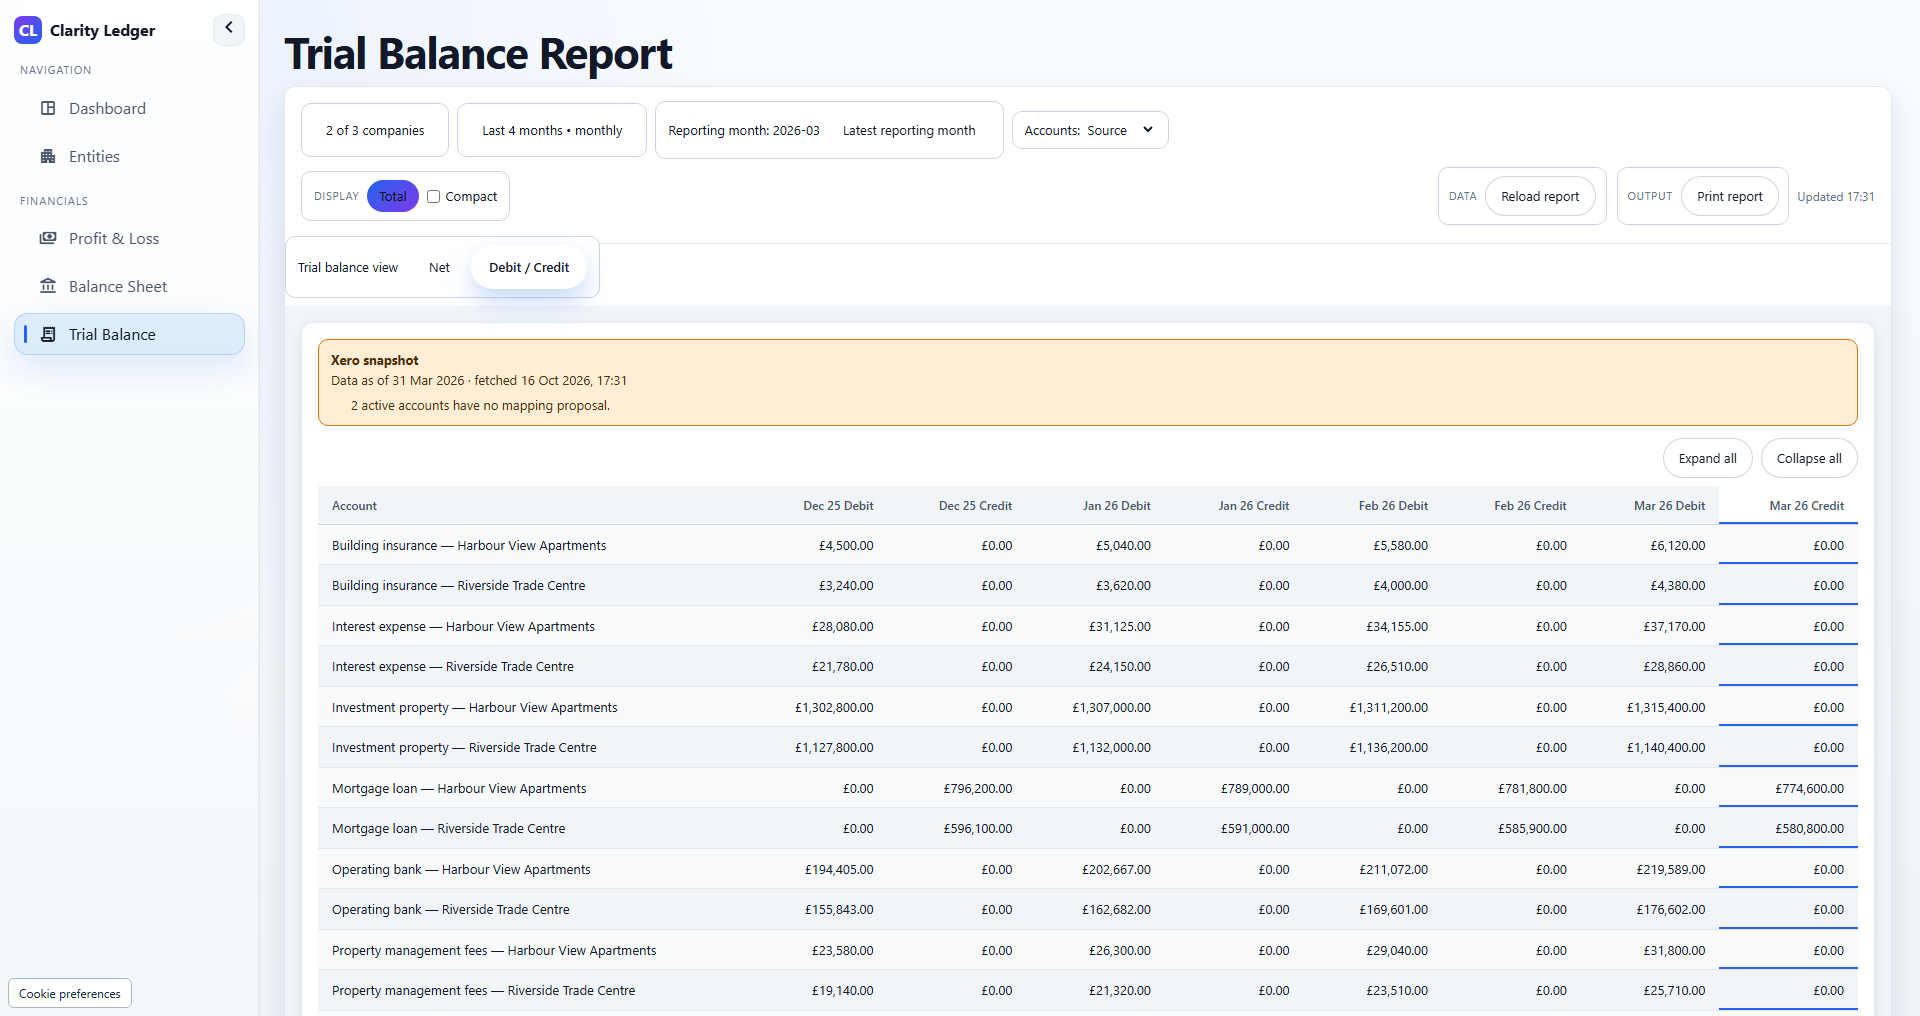
Actual Clarity Ledger trial balance report · Illustrative demo data
A month-end close checklist for property SPVs
Practical, evidence-based close routine for rent-led SPVs-cash, rent roll tie-outs, service charge, capex vs opex, debt and covenants-plus a downloadable PDF checklist you can use this month.
Ready for portfolio-grade reporting?
Review Xero, QuickBooks Online and FreeAgent companies in one dashboard, with saved financial reports and account mappings you apply. A 21-day trial is available once per eligible portfolio.