How to make portfolio reporting consistent across assets and SPVs
A practical framework to make SPV-based portfolio reporting reconcilable, comparable, and explainable-definitions, portfolio COA + mappings, governance, and drillable delivery.
Integration update, 20 October 2026: Clarity Ledger now connects Xero, QuickBooks Online and FreeAgent. GBP Xero examples below remain valid. Check current provider and currency eligibility; planning, KPI and pack-preparation tasks described as manual remain separate workflows.
This educational framework includes manual controls and external tools. Transaction drill-through, automatic eliminations, effective-dated mapping governance and automated pack generation described as requirements below are not live Clarity Ledger features.
So your numbers reconcile, your KPIs mean the same thing everywhere, and your dashboard becomes something people actually trust.
If you manage a portfolio through multiple assets and SPVs, you have probably seen this happen:
- Asset A looks like it is outperforming Asset B... until you realise they classify capex differently.
- The "portfolio NOI" on the dashboard does not tie back to the sum of SPV P&Ls.
- Month-end becomes a cycle of exports, mapping fixes, and "recon bridges" nobody wants to repeat.
- Stakeholders stop asking "what does the data say?" and start asking "can we trust it?"
The uncomfortable truth is that portfolio reporting usually fails for one simple reason:
The portfolio is not speaking one financial language.
Consistency is not a formatting problem. It is a data model + governance problem.
This post lays out a practical framework to make portfolio reporting consistent across assets and SPVs-without turning month-end into a major project.
What "consistent reporting" actually means
A consistent portfolio view has three properties:
1) It reconciles
Portfolio totals tie back to entity-level financial statements (with clear, documented adjustments such as eliminations).
2) It is comparable
"NOI" means the same thing in every asset and SPV. So do capex buckets, finance costs, operating expenses, and revenue categories.
3) It is explainable
You can drill from portfolio -> asset/SPV -> account -> transaction detail to answer "why did this change?" quickly.
If you are missing any one of these, your dashboard will feel "directional" instead of decision-grade.
Why SPV portfolios drift into inconsistency
Most portfolios do not set out to become inconsistent. It happens gradually:
- Different bookkeepers/accountants set up slightly different charts of accounts (COAs).
- Property managers code invoices differently across assets.
- New accounts get created mid-year to solve a local issue ("Emergency repairs", "Insurance - other").
- Capex vs opex gets blurred under time pressure.
- Service charge / recoveries get treated gross in one SPV and net in another.
- One-off journals get posted without a portfolio view in mind.
Individually, each SPV can look "fine." But at portfolio level, those differences become reporting noise-and reconciliation pain.
The solution: treat reporting consistency like infrastructure
The fastest path to consistency is to build a simple "reporting operating system" with four layers:
- Definitions (what your KPIs and categories mean)
- Structure (portfolio COA + mappings)
- Process (month-end controls + change governance)
- Delivery (consolidation + drillable dashboards)
Let us break those down.
1) Definitions: standardise the portfolio's financial language
Before you touch a dashboard, align on definitions. Otherwise you will automate inconsistency.
Start with a one-page "Portfolio Reporting Spec"
This document becomes your reference point for every SPV and asset. Keep it short and practical.
Include:
KPI definitions
- NOI: what is included, what is excluded (and why)
- Operating expenses: what sits here vs below NOI
- Capex: what qualifies, and what does not
- Finance costs: interest vs fees vs hedging
- Cash: which accounts count, what is restricted, what is excluded
Policy decisions (the ones that always cause drift)
- Capex vs repairs policy (and examples)
- Gross vs net treatment for recoveries/service charge
- Treatment of void costs and leasing fees
- Treatment of refurb downtime and incentives
Tip: Investors do not mind which definition you use-they mind when it changes without warning.
2) Structure: create a Portfolio COA and map every SPV to it
This is the biggest unlock for consistent reporting across SPVs.
Build a Portfolio Chart of Accounts (Portfolio COA)
Think of this as your canonical reporting structure-the lines your board and investors expect, regardless of what each SPV's Xero or QuickBooks file looks like.
A practical real estate Portfolio COA usually includes:
Income
- Gross rent
- Recoveries / service charge income
- Other income
Operating expenses
- Property management
- Repairs & maintenance
- Utilities / services
- Insurance
- Rates / taxes
- Professional fees
- Other operating costs
NOI
Capex (separate buckets)
- Refurb / value-add capex
- Lifecycle capex
- Compliance capex
- ESG / efficiency capex
Finance
- Interest
- Fees
- Hedge costs (if relevant)
Balance sheet (for integrity + drill-down)
- Cash
- Receivables / arrears
- Payables / accruals
- Debt balances
- Intercompany (if applicable)
The point is not to over-engineer your COA. It is to ensure every SPV can roll up cleanly to a shared set of headings.
Add a mapping layer (because SPVs will never stay identical)
Even with standardisation, SPVs drift. So you need an explicit mapping layer that translates:
SPV account (Xero or QuickBooks) -> Portfolio COA line
A mapping layer is the difference between:
- "We consolidate if everyone behaves perfectly," and
- "We consolidate reliably even when reality changes."
Non-negotiable rules for mapping
- Every active account must be mapped (no silent "other")
- Unmapped accounts must be flagged immediately
- Mapping changes must be auditable (who changed what, when, and why)
- Effective dating should be supported (so you do not accidentally rewrite history)
This is how you keep month-end consistent even when someone adds a new nominal code tomorrow.
3) Process: enforce consistency with lightweight governance
Most teams do not need heavy controls. They need repeatable controls.
A monthly close rhythm that protects reporting quality
Consistency collapses when month-end is messy. Your close process should include:
Minimum entity-level checks (per SPV)
- Bank reconciliation complete
- Key balance sheet reconciliations reviewed (cash, debt, payables)
- Capex postings reviewed (especially refurb-related spend)
- Period locked (so numbers do not shift after consolidation)
Portfolio-level checks (across SPVs)
- Unmapped accounts report reviewed and resolved
- Variance outliers flagged (large moves, unusual coding)
- Intercompany movements identified (if applicable)
Prevent COA drift with two simple controls
-
New account approval (light-touch)
- If someone creates a new account, it triggers a mapping review.
-
Account templates for new SPVs
- New SPVs inherit a standard COA structure and naming conventions.
This avoids the "every SPV is unique" trap that kills consolidation.
4) Delivery: consolidate once, then make it drillable
Once definitions, structure, and process are in place, delivery becomes straightforward:
- Consolidate at portfolio level
- Present consistent KPIs
- Enable drill-down so the dashboard is explainable
Make drill-down a requirement, not a "nice to have"
A trusted dashboard lets you answer these questions quickly:
- "Which SPVs drove the NOI change?"
- "Which accounts changed most?"
- "What transactions explain the variance?"
- "Is this capex or opex-and why?"
- "Is cash tight in one SPV or across the portfolio?"
If you cannot drill, your reporting will always feel like a presentation layer-not an operating tool.
The consistency scorecard: 6 tests that tell you if you have got it right
If you want a simple way to assess whether your portfolio reporting is consistent, run these checks:
- Cash ties: portfolio cash equals the sum of SPV cash (by bank accounts)
- Revenue ties: portfolio revenue equals the sum of SPV revenue (after documented adjustments)
- NOI definition holds: NOI is calculated the same way across all SPVs
- Capex classification is stable: refurb and lifecycle spend land in consistent buckets
- Unmapped accounts are zero: nothing sits outside your mapping layer
- Drill-down works: every portfolio line can be traced to SPV + account + transactions
If any of those fail, your reporting is not "wrong"-it is just not finished.
A practical 30-60-90 day plan to get consistent
If you are starting from "Excel rollups and inconsistencies," here is a realistic rollout sequence.
Days 0-30: define and stabilise
- Write the Portfolio Reporting Spec (definitions + examples)
- Create your Portfolio COA
- Identify priority KPIs (NOI, capex buckets, finance costs, cash)
Days 31-60: map and reconcile
- Map SPV COAs to Portfolio COA
- Resolve unmapped accounts and duplicates
- Implement the unmapped-account alert process
- Prove reconciliation for a single month end-to-end
Days 61-90: automate and operationalise
- Build consolidated dashboards with drill-down
- Embed close checks and period locks
- Set up a cadence for monthly commentary (what changed, why, risks)
This approach stops you chasing perfection upfront and gets you to "trusted and repeatable" quickly.
Why this matters beyond reporting
Once your reporting is consistent, you unlock higher-value work:
- budgeting and rolling forecasts that do not fall apart across entities
- scenario planning (rates, occupancy, refurb programmes) with clean cash impacts
- investor narratives built on reconciled numbers
- faster decision-making because performance discussions start with "what do we do?" instead of "can we trust this?"
Consistency is not just reporting hygiene-it is an operating advantage.
Apply the framework to the current reporting workflow
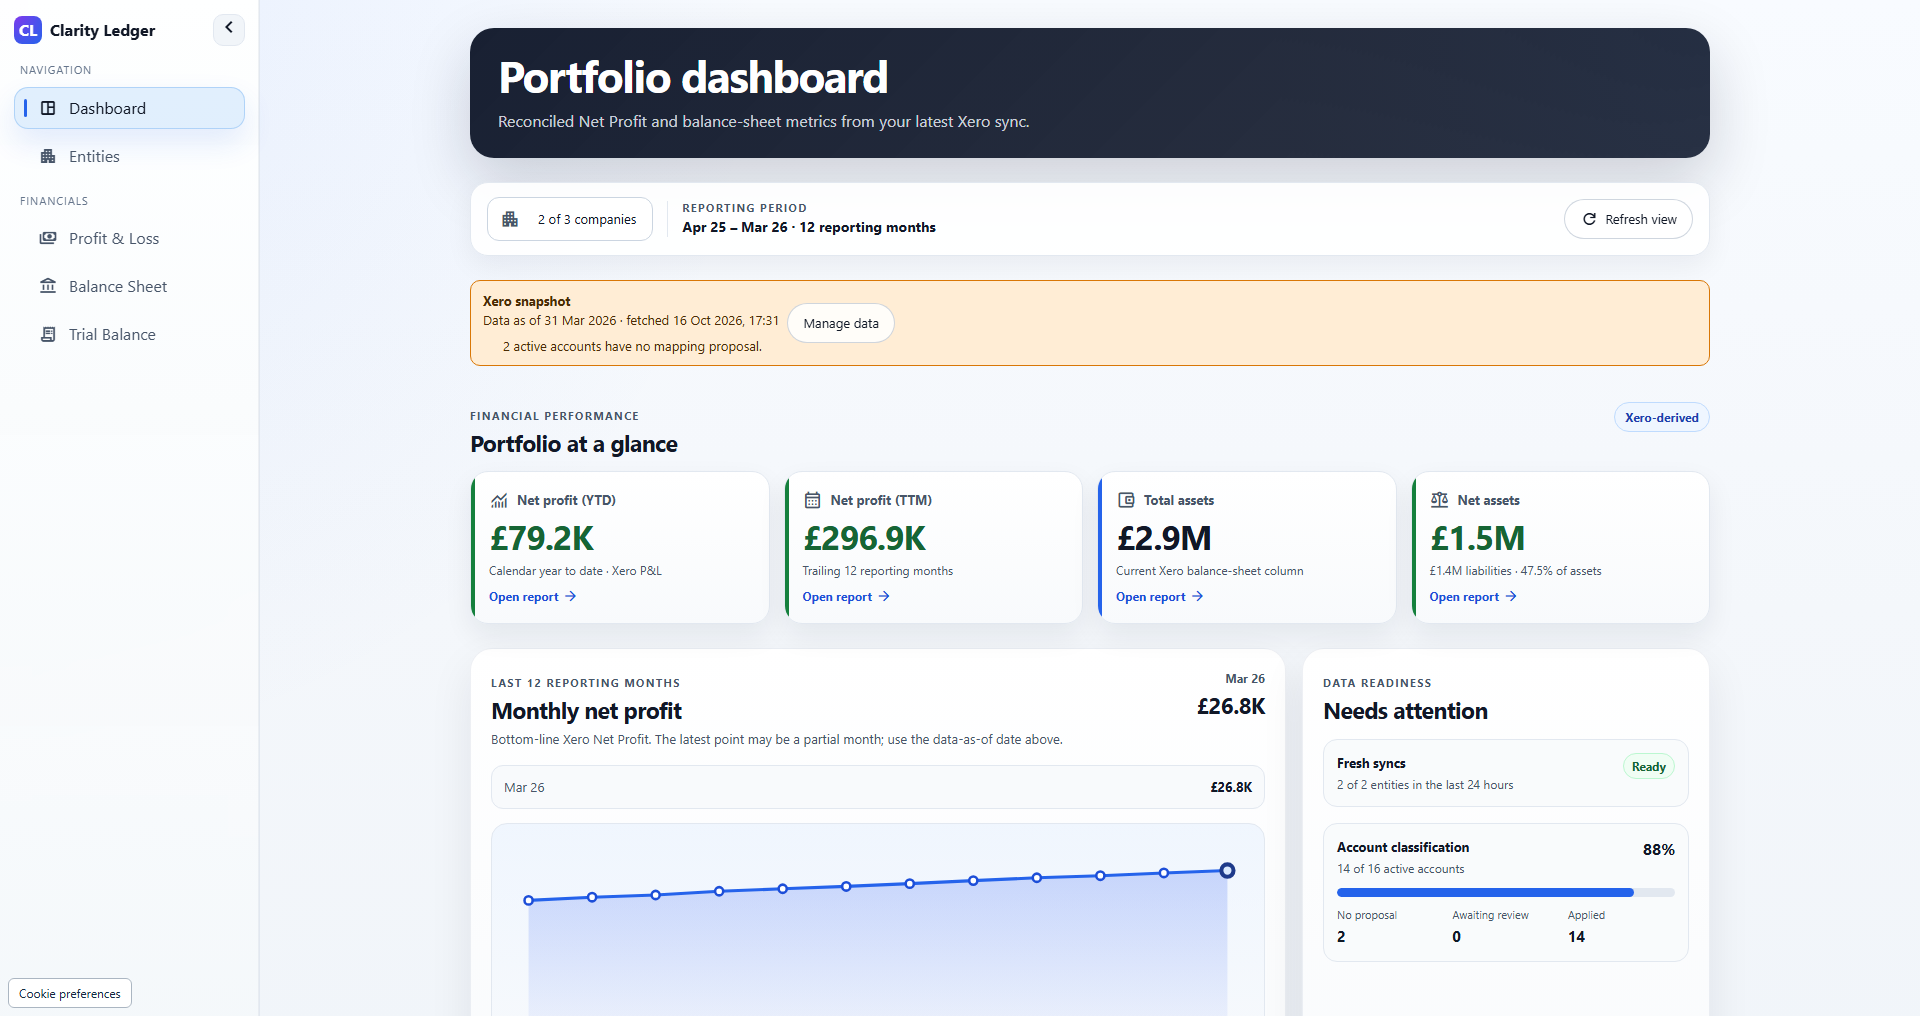
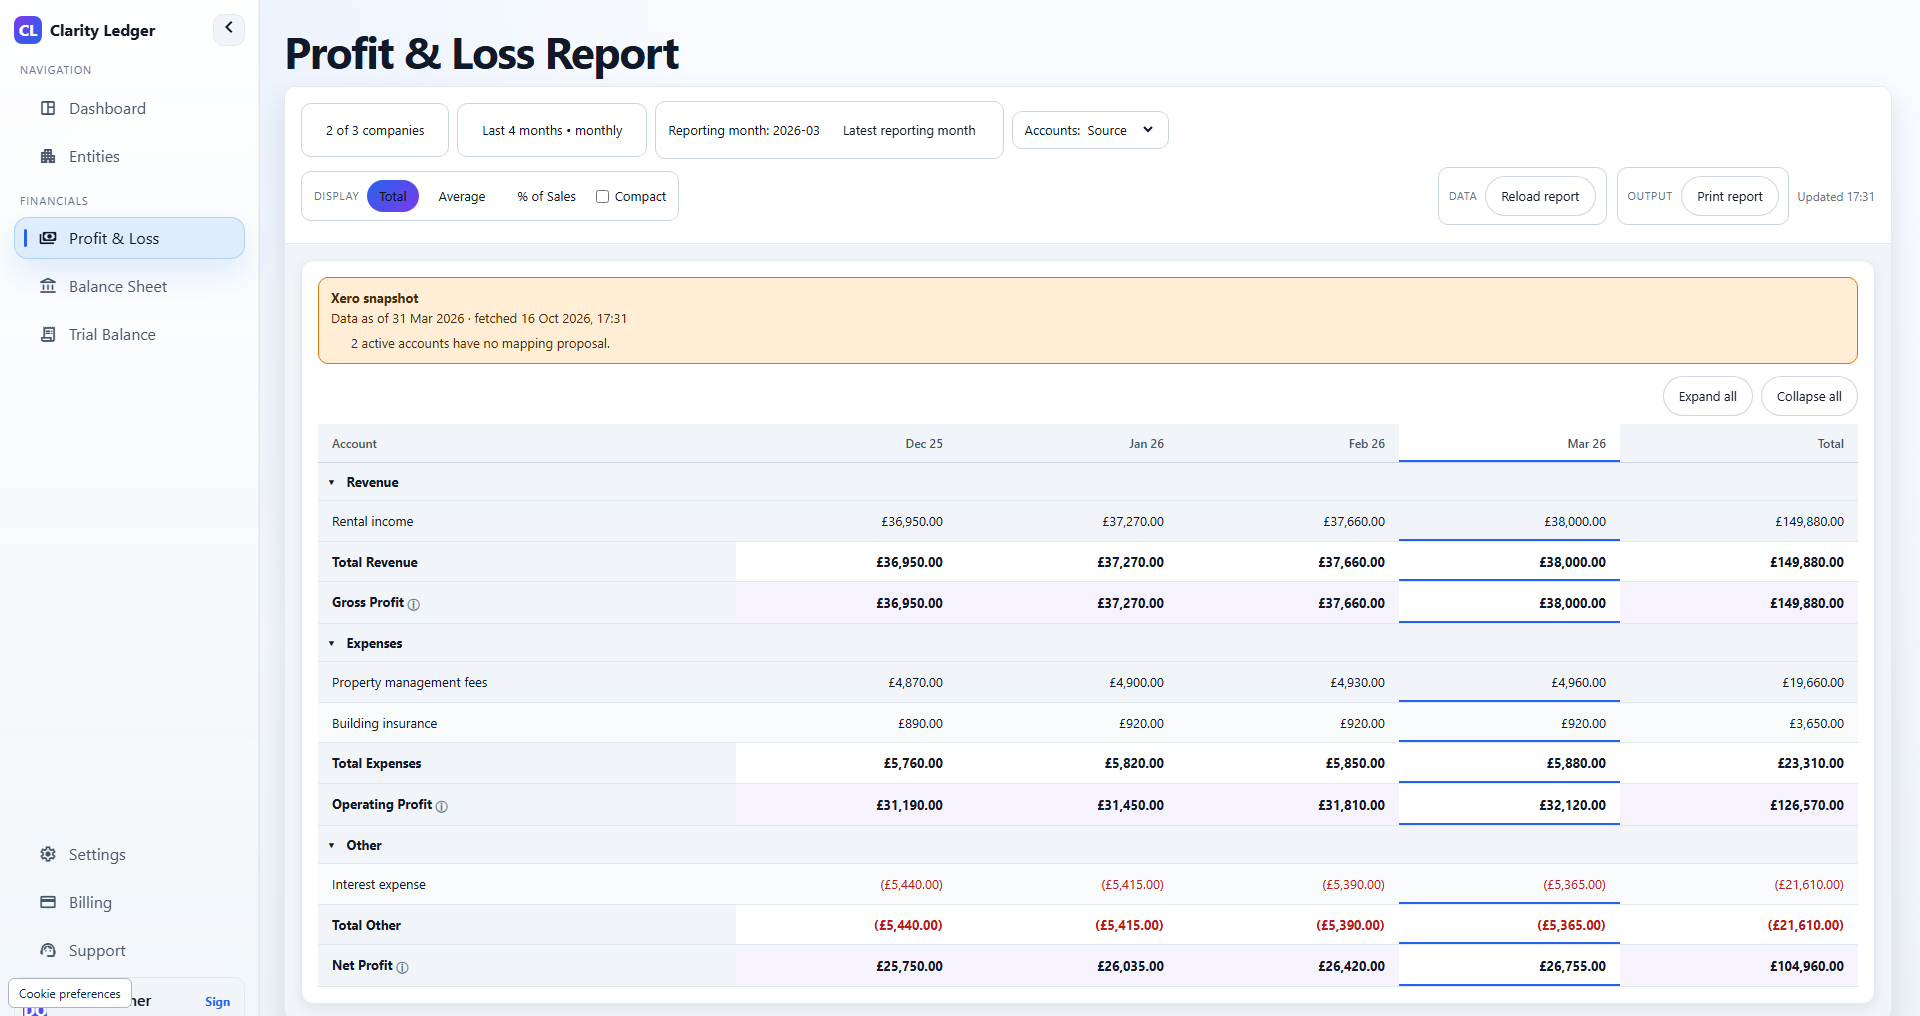
Clarity Ledger stores historical P&L, balance sheet and trial balance reports after a successful sync from eligible Xero, QuickBooks Online and FreeAgent companies. Source reports retain the provider's account classifications; Standard reports use the account mappings you review and apply.
Before comparing companies, make these checks:
- Confirm the provider and currency scope. Xero and QuickBooks Online support GBP, EUR or USD base/home currencies. FreeAgent support covers UK GBP limited companies. Check each company's eligibility before connecting it; the providers do not have identical coverage.
- Match the evidence before combining it. Compare the same company, report, dates and accounting basis in its source ledger and Source report. Check the latest successful sync and any warnings. A saved report does not show ledger changes made after that sync.
- Review classifications separately from amounts. Use the account-mapping guide to document which local accounts belong in each reporting line, then review mapping gaps in Standard reports. A classification change is not a correction to the source bookkeeping.
- Keep native and presented currency distinct. Compare a native-currency report with the matching source report. For GBP management presentation of EUR or USD companies, review exchange-rate coverage for the selected periods before comparing translated totals. FreeAgent imports remain GBP.
The two-SPV Xero worked example shows how selected account lines can reconcile before and after mapping. Its fictional subtotal is not a full P&L or a ready-made calculation of NOI. Use the reconciliation routine to keep source-ledger checks separate from this reporting review.
The broader operating model in this guide still needs separately maintained KPI definitions, close evidence, intercompany adjustments and transaction review in the source ledger. Forecasting, scenarios, AI commentary and investor-pack generation are not enabled. See the current product scope.
More operations insights for real estate finance teams.
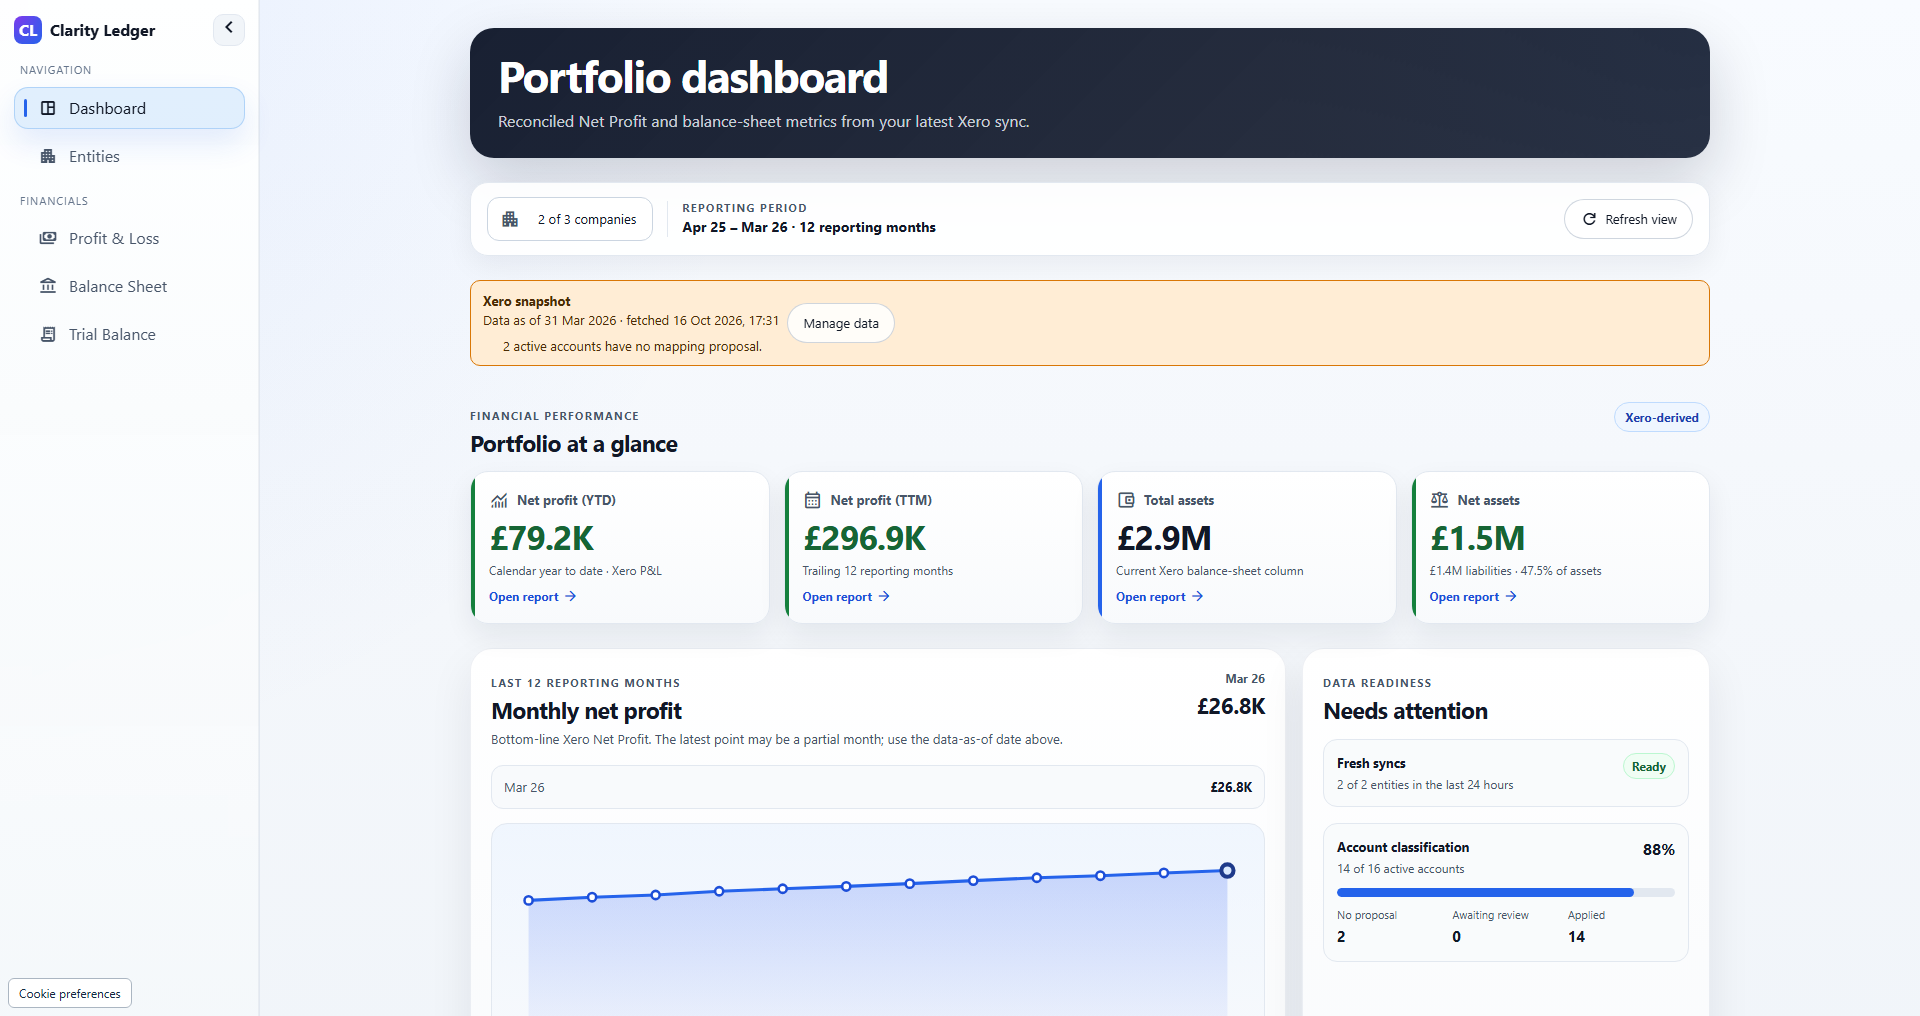
Actual Clarity Ledger portfolio dashboard · Illustrative demo data
Release notes that matter: what changed and why it helps finance teams
A finance-grade release note template that answers what changed, who is affected, why it matters, what to do, and how to validate-so multi-entity teams keep reconciliations, definitions, and trust intact.
Actual Clarity Ledger portfolio dashboard · Illustrative demo data
From raw accounting data to investor KPIs: a manual reporting framework
A manual investor KPI framework: align SPV inputs, document mappings and roll-up rules, calculate metrics separately, and reconcile outputs to evidence.
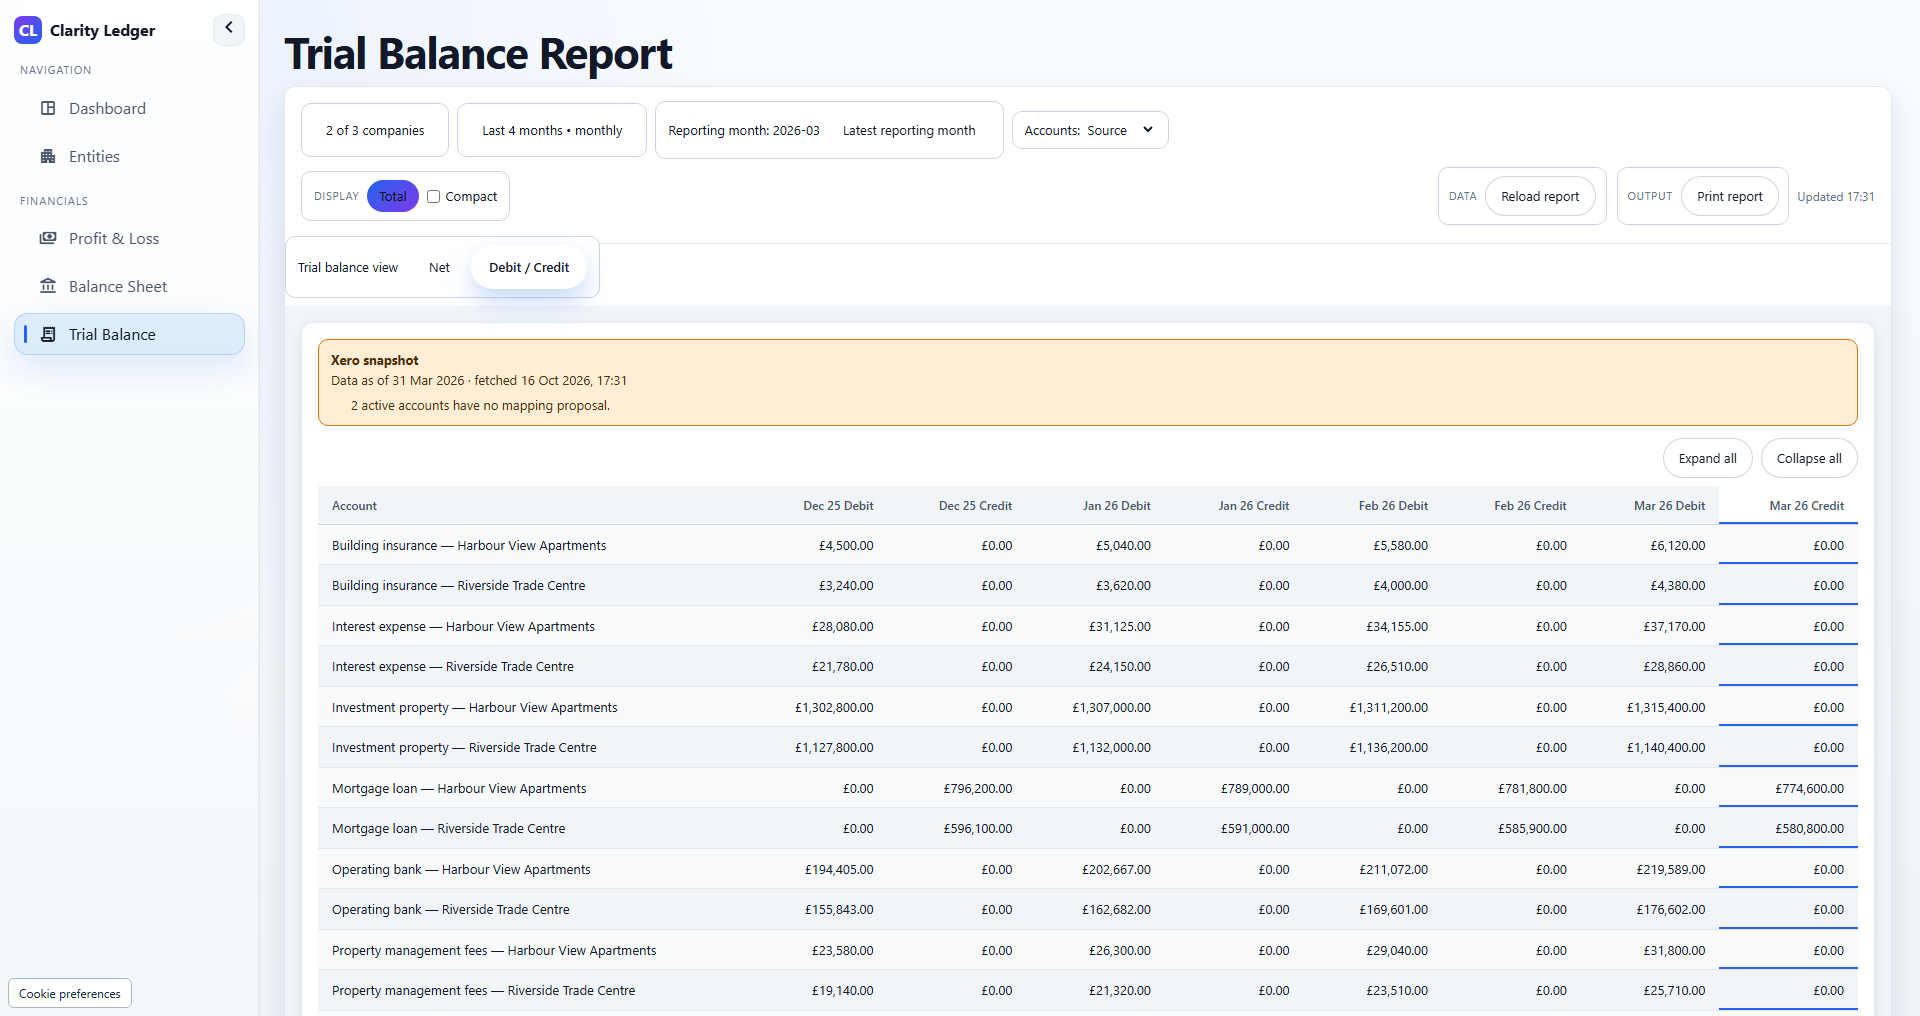
Actual Clarity Ledger trial balance report · Illustrative demo data
A month-end close checklist for property SPVs
Practical, evidence-based close routine for rent-led SPVs-cash, rent roll tie-outs, service charge, capex vs opex, debt and covenants-plus a downloadable PDF checklist you can use this month.
Ready for portfolio-grade reporting?
Review Xero, QuickBooks Online and FreeAgent companies in one dashboard, with saved financial reports and account mappings you apply. A 21-day trial is available once per eligible portfolio.