Month-end close across 10/25/100 SPVs: a repeatable workflow
A scalable month-end close for property SPVs: standardise, parallelise, review exceptions, and roll up to a portfolio view you can trust-whether you have 10 or 100 entities.
Integration update, 20 October 2026: Clarity Ledger now connects Xero, QuickBooks Online and FreeAgent. GBP Xero examples below remain valid. Check current provider and currency eligibility; planning, KPI and pack-preparation tasks described as manual remain separate workflows.
This is a finance-team workflow performed in source ledgers and separate schedules. Clarity Ledger supplies saved historical reports for selected GBP-base Xero companies after successful sync; close management, automatic eliminations, transaction drill-through, forecasts, AI commentary and investor packs are not enabled.
Closing one SPV is bookkeeping. Closing 10, 25, or 100 SPVs is operations.
The difference is not accounting complexity-it is workflow complexity: coordinating inputs, setting cutoffs, handling exceptions, and producing a portfolio view that is consistent enough to trust (and fast enough to matter).
This post outlines a close workflow that finance teams can adapt as entity count grows. It requires named owners, source-ledger work and supporting schedules; the examples do not establish tested app capacity or guaranteed time savings.
The core problem: SPV close fails at scale for predictable reasons
Across property portfolios, month-end close usually breaks down because:
- Inputs arrive inconsistently (rent reports, bank statements, invoices, capex updates).
- Definitions drift (NOI, capex vs opex, one-offs, management fees).
- Each SPV becomes its own mini-universe (different charts of accounts, different practices).
- Portfolio reporting is a separate "second close" (manual consolidation after entity closes).
- Too much time is spent reviewing everything, instead of reviewing what matters.
A scalable close is not "do more work faster." It is "do the same work with fewer surprises."
What "good" looks like (regardless of SPV count)
A strong multi-SPV month-end close has four traits:
-
Standardised
Everyone uses the same checklists, cutoffs, and reporting definitions. -
Parallelised
SPVs close in parallel with clear owners, not sequentially in a bottleneck. -
Exception-based
You review anomalies and threshold breaches-not every line item, every month. -
Portfolio-first
The portfolio roll-up is not an afterthought; it is built into the workflow.
The repeatable workflow: 7 stages (that scale cleanly)
Stage 0: Pre-close (Day -5 to Day -1) - remove avoidable surprises
Goal: Complete known preparation before month-end and record outstanding inputs.
Minimum viable pre-close checklist
- Bank feeds are running; missing bank accounts flagged
- AP is current; known late invoices flagged
- Capex tracker updated (what was spent, what is committed)
- Rent/occupancy data readiness confirmed (even if final report lands on Day 1)
- Intercompany items flagged (management fees, recharge, loans)
- Issues log opened (one place to capture problems and decisions)
Why this matters at 25/100 SPVs: pre-close is where you prevent the "Day 7 scramble."
Stage 1: Close kickoff (Day 0) - set the rules of the month
Goal: Establish cutoffs and expectations once, so you do not renegotiate them 100 times.
At kickoff, define:
- The close calendar (dates + times, with owners)
- The cutoff policy (what gets accrued, what waits, materiality threshold)
- The pack outputs you are producing this month (dashboard, investor pack, lender reporting)
- The definition snapshot (NOI definition, capex policy, one-off tagging rules)
This is where you protect consistency-especially when staff, property managers, or external bookkeepers vary by SPV.
Stage 2: Transaction completeness (Day 0 to Day 3) - "did we capture reality?"
Goal: Each SPV has a complete base before you start explaining variances.
For each SPV, complete:
- Bank reconciliation (all bank accounts, not just the main ops account)
- AR: rent posted, receipts matched, arrears visible
- AP: invoices coded, recurring bills posted
- Accruals: utilities, maintenance, professional fees (as per cutoff rules)
- Debt & interest: interest accruals consistent with loan terms
- Basic balance sheet sanity: cash, payables, intercompany, prepaids
Scaling tip: Use a simple status grid:
- Green = complete and reconciled
- Amber = complete but awaiting one input
- Red = incomplete / cannot close
At 100 SPVs, you are managing a factory line-status visibility is half the battle.
Stage 3: Standard adjustments & classifications (Day 2 to Day 4) - keep NOI clean
Goal: The same transactions get treated the same way across entities.
Standardise these adjustments:
- Capex vs OpEx (repairs vs improvements)
- One-off tagging (legal settlements, major repairs, insurance true-ups)
- Management fees & recharges (consistent recognition and coding)
- Intercompany balances (due to/from cleaned up or clearly separated)
- Prepayments (insurance, service contracts)
- Depreciation (if included in management reporting) vs "below NOI" treatment
This is where many portfolios lose comparability. If SPV A puts a refurb invoice in OpEx and SPV B puts it in Capex, your portfolio NOI story becomes noise.
Stage 4: Entity sign-off (Day 3 to Day 5) - lock the building blocks
Goal: Each SPV's results are final enough to consolidate.
For sign-off, require:
- Reconciled cash
- Approved accruals and key journals
- Notes for any estimates / missing inputs
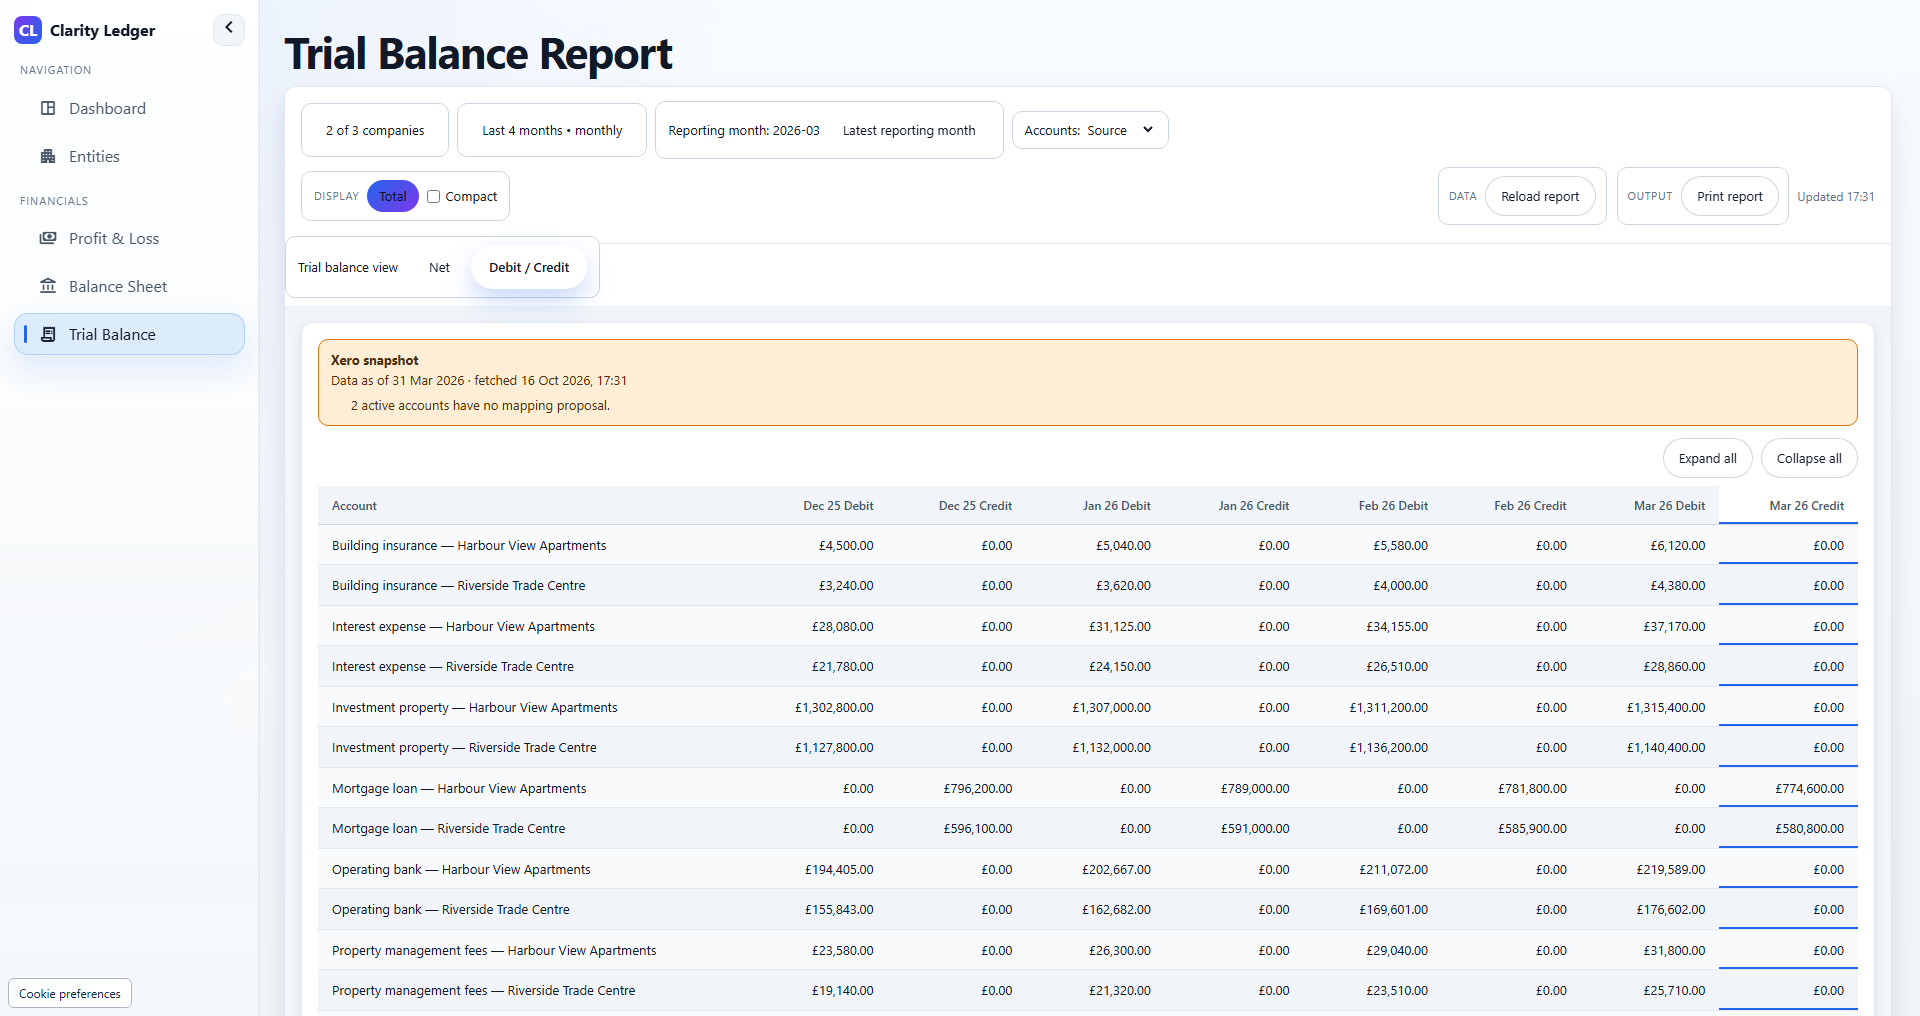
- Trial balance exported (or synced) into the portfolio layer
- Period "locked" (or at least controlled)
Important mindset: Do not wait for perfection across 100 SPVs.
Instead: sign off in waves, with clear "final vs estimated" flags and a defined true-up process.
Stage 5: Portfolio consolidation (Day 4 to Day 6) - turn 100 truths into one truth
Goal: Produce a portfolio view that is consistent, explainable, and drillable.
Minimum viable consolidation rules:
-
Standardised mapping (local SPV accounts -> standard reporting lines)
-
Ownership handling (100% + investor share, or pro-rata-choose and document)
-
Intercompany treatment (eliminate where reliable; otherwise isolate as a separate line)
-
Consolidation checks:
- cash tie-out vs bank balances
- "other" bucket size (should trend down over time)
- variance outliers vs last month/budget
- missing SPVs flagged
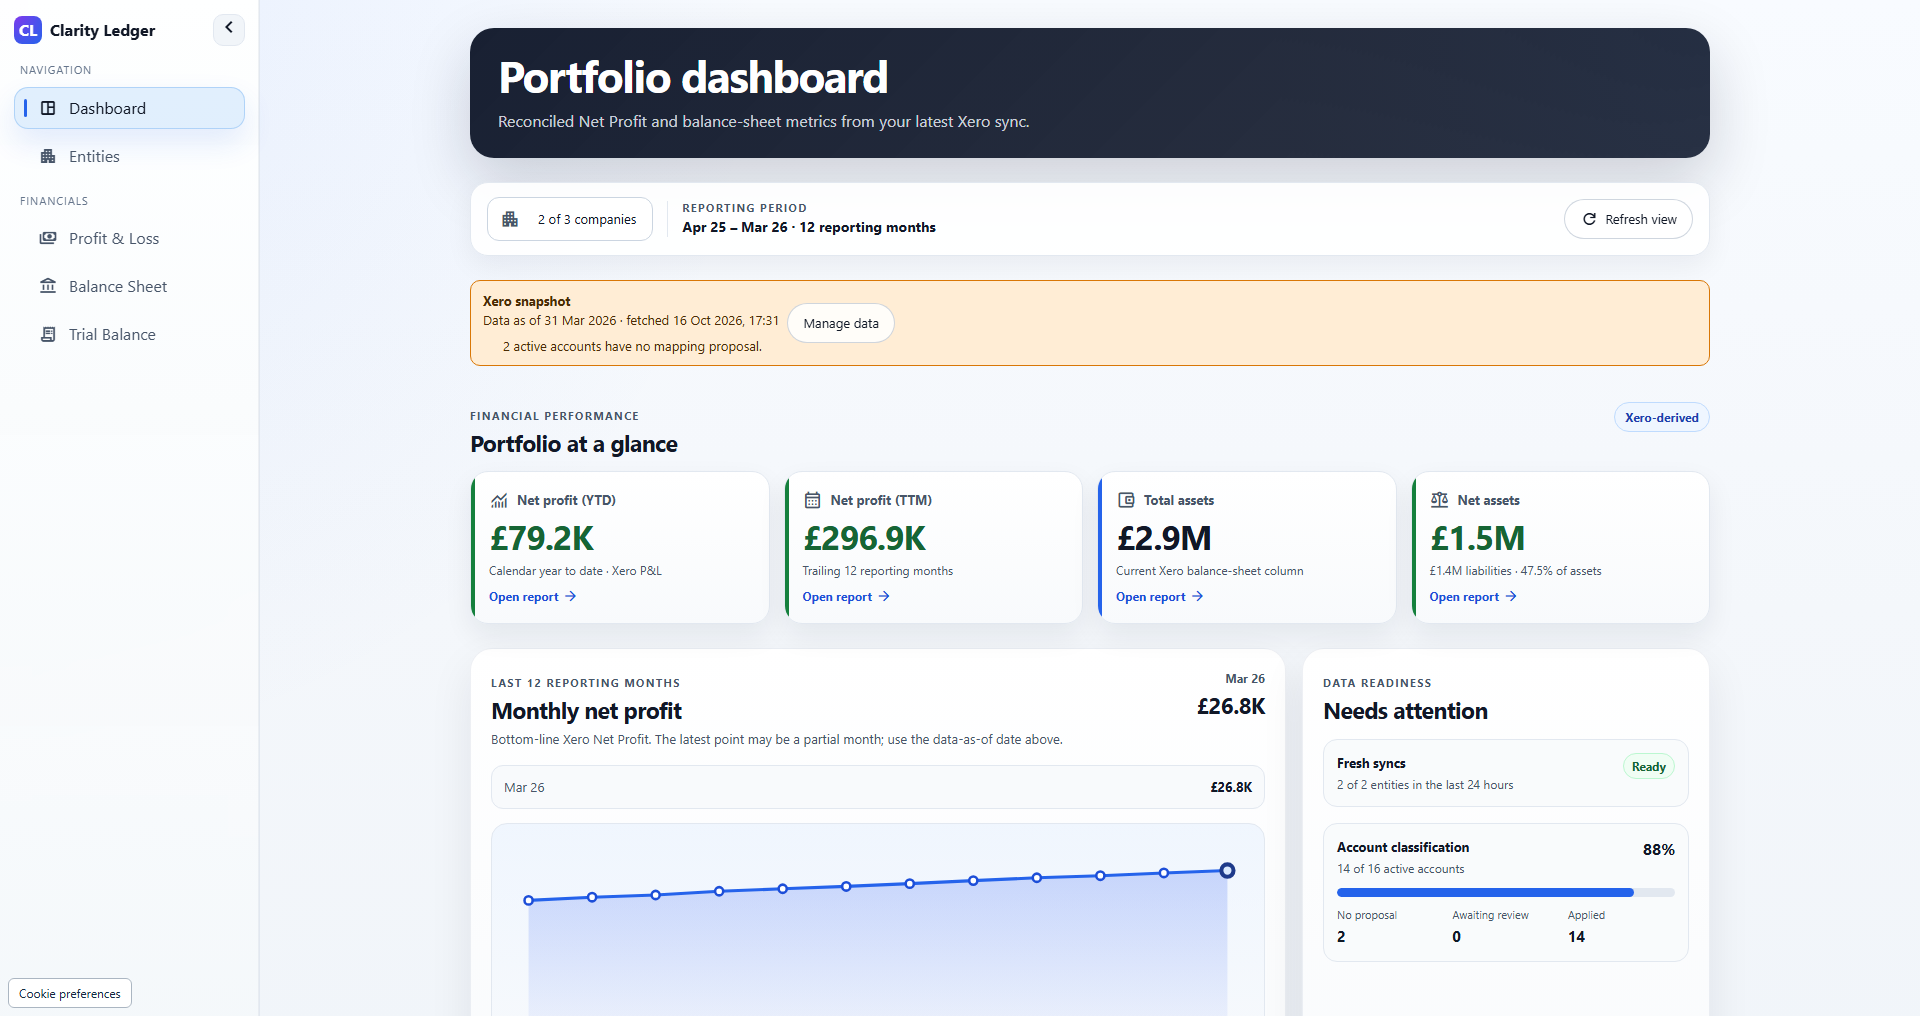
At this stage, the best setups use a one-stop portfolio view across multiple entities (SPVs) with standardised chart of accounts and mappings so everything rolls up cleanly-because manual consolidation becomes the limiting factor as you scale.
Stage 6: Review & commentary (Day 5 to Day 7) - shift from "numbers" to "insight"
Goal: Explain what changed, why it changed, and what to do next.
A repeatable review rhythm:
- Portfolio headline: Revenue / OpEx / NOI (MTD + YTD)
- Asset ranking: strongest/weakest (NOI, margin, occupancy)
- Variance bridges: top drivers only (by materiality threshold)
- Cash movements: operational vs capex vs financing
- Risks to watch: covenant headroom, arrears trend, interest exposure, capex overruns
If you use a separate AI tool to draft commentary, provide mapped figures and documented drivers, then verify every statement. These inputs do not prevent a model from inventing causes.
Stage 7: Post-close (Day 7 to Day 10) - fix the process, not just the month
Goal: Reduce work next month.
Run a short post-close retro:
- Which SPVs were late-and why?
- Which mappings changed-and should they?
- Which "one-offs" will recur?
- What caused the biggest rework?
- What can be moved into pre-close?
This is how you turn close into a system, not a fire drill.
How the workflow changes at 10 vs 25 vs 100 SPVs
At ~10 SPVs: "Disciplined manual" can work
- Shared close checklist
- Spreadsheet status tracker
- Standard pack template
- Light mapping
Main risk: everything lives in one person's head.
At ~25 SPVs: you need standardisation + mapping, or you will stall
- Standard reporting structure becomes non-negotiable
- Mapping layer required for apples-to-apples reporting
- Variance thresholds and exception review become essential
Main risk: portfolio reporting becomes a second close.
At ~100 SPVs: you need a "close factory"
- Parallel close by pods (e.g., by region/manager/lender)
- Automated TB pulls / synced data
- Exception-based controls (review what is abnormal)
- Centralised consolidation + drill-down
- Clear audit trail and mapping governance
Main risk: drowning in volume and losing confidence in the numbers.
The minimum viable artifacts (templates) that make this repeatable
If you want this to run smoothly month after month, create these once and reuse them:
- Close calendar (with owners + deadlines)
- SPV close checklist (bank rec, accruals, debt, interco, capex, sign-off)
- Issues log (decisions, missing inputs, estimates, follow-ups)
- Standard reporting structure (portfolio chart / reporting lines)
- Mapping table (SPV accounts -> standard lines)
- Variance thresholds (what triggers review)
- Pack template (portfolio dashboard + consistent sections)
The goal is to make close boring.
KPIs to track (so you know if the workflow is improving)
A few metrics go a long way:
- Days to close (portfolio-level)
- % of SPVs closed by Day 5
- # of post-close adjustments
- Bank rec completion rate
- Mapping exceptions (unmapped accounts, "other" bucket size)
- Variance review yield (how many exceptions were real issues vs noise)
When these improve, everything else improves: confidence, speed, and investor responsiveness.
Where the workflow goes next
Once your close is repeatable, you can layer on:
- portfolio budgeting and forecasting,
- cash flow planning,
- "what-if" scenario planning (rates, occupancy, refurb timing),
- and automated investor/board packs with consistent logic and commentary.
That is when finance stops chasing data and starts steering decisions.
More operations insights for real estate finance teams.
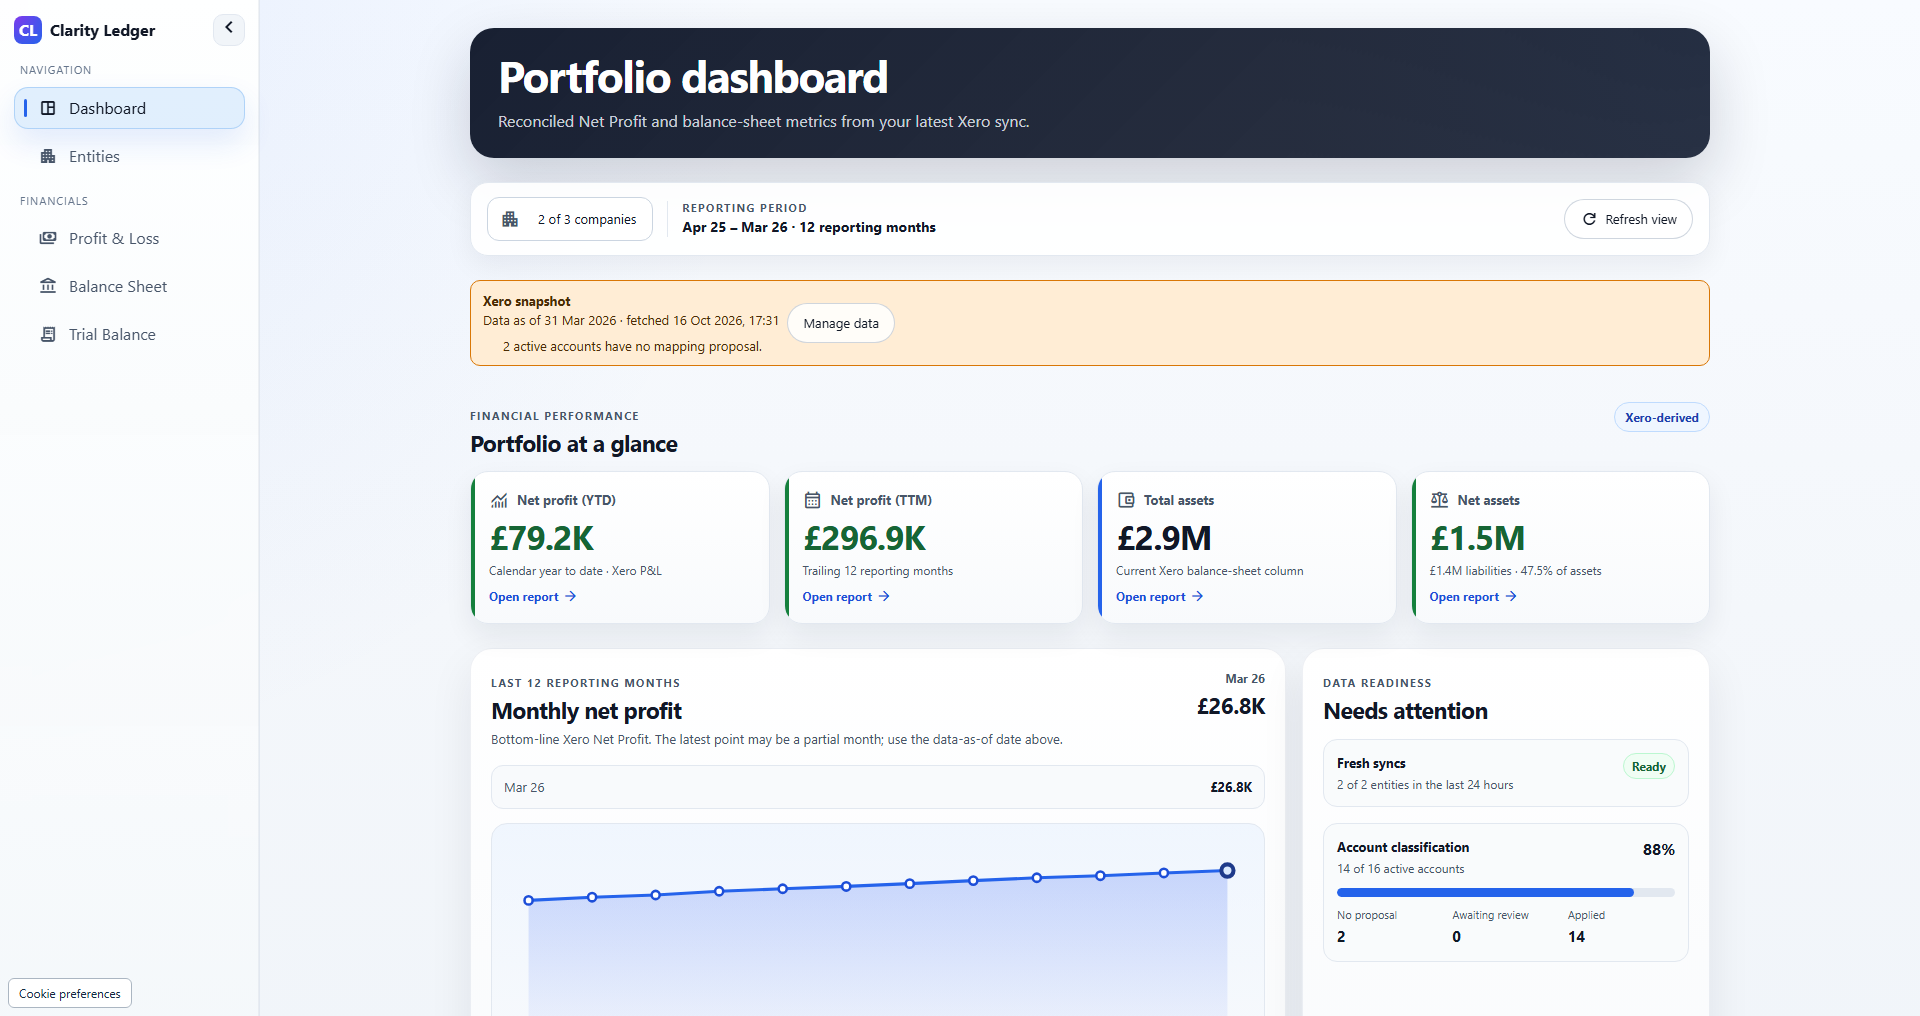
Actual Clarity Ledger portfolio dashboard · Illustrative demo data
Release notes that matter: what changed and why it helps finance teams
A finance-grade release note template that answers what changed, who is affected, why it matters, what to do, and how to validate-so multi-entity teams keep reconciliations, definitions, and trust intact.
Actual Clarity Ledger portfolio dashboard · Illustrative demo data
From raw accounting data to investor KPIs: a manual reporting framework
A manual investor KPI framework: align SPV inputs, document mappings and roll-up rules, calculate metrics separately, and reconcile outputs to evidence.
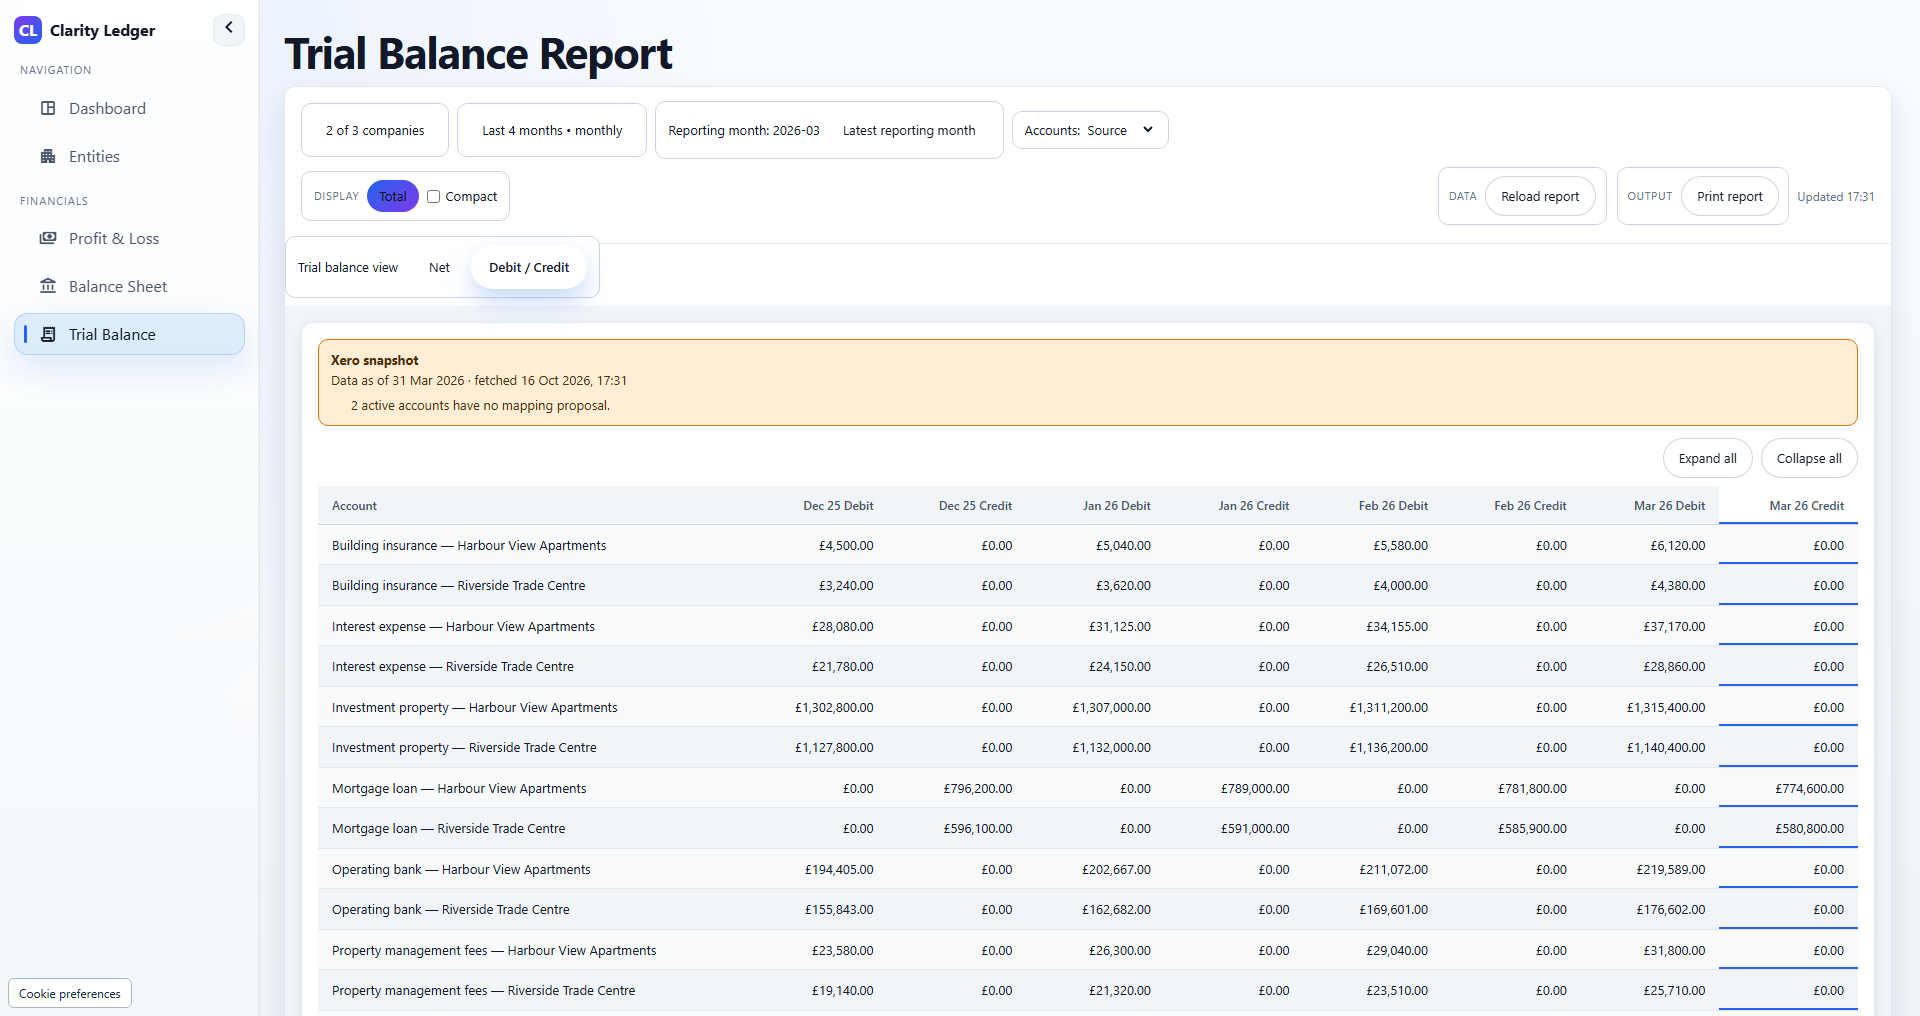
Actual Clarity Ledger trial balance report · Illustrative demo data
A month-end close checklist for property SPVs
Practical, evidence-based close routine for rent-led SPVs-cash, rent roll tie-outs, service charge, capex vs opex, debt and covenants-plus a downloadable PDF checklist you can use this month.
Ready for portfolio-grade reporting?
Review Xero, QuickBooks Online and FreeAgent companies in one dashboard, with saved financial reports and account mappings you apply. A 21-day trial is available once per eligible portfolio.