Stress testing a portfolio: 5 scenarios every CFO should run quarterly
A repeatable quarterly stress test set for multi-SPV portfolios: rates + hedge roll-off, occupancy/collections, non-recoverable OpEx, refurb slip, and refinance squeeze-tied to cash, covenants, and actions.
Integration update, 20 October 2026: Clarity Ledger now connects Xero, QuickBooks Online and FreeAgent. GBP Xero examples below remain valid. Check current provider and currency eligibility; planning, KPI and pack-preparation tasks described as manual remain separate workflows.
This is a guide to stress tests you run in your own model. Clarity Ledger does not provide stress-testing, forecasting or scenario-planning tools; its current offer covers historical GBP Xero reports and reviewed mappings.
Property portfolios rarely fail because of one bad month. They fail because risk builds quietly across cash, covenants, refinancing, and operational performance-until one trigger turns "manageable" into "urgent."
Quarterly stress testing is how CFOs stay ahead of that curve. Not with a giant bespoke model that nobody wants to touch again-but with a repeatable set of scenarios that answer one question:
If conditions move against us, where do we break first-and what would we do about it?
Below are five scenarios worth running every quarter across property groups (especially multi-SPV portfolios), plus the common mistakes that make stress testing misleading and the best-practice way to report results so leadership can actually act.
Why quarterly?
Monthly is often too noisy (timing, cutoffs, one-offs). Annually is too slow (risk evolves faster than budgets). Quarterly is the sweet spot because it aligns with:
- refinancing and lender conversations,
- capex programme governance,
- portfolio reforecast cadence,
- and the reality that macro drivers (rates, spreads, liquidity) can shift meaningfully in a quarter.
The goal is not to predict the future. It is to measure resilience-and to build muscle memory in decision-making.
What good stress testing looks like
A stress test is useful when it produces:
- A clear "break point"
- the week/month cash goes negative, or
- the covenant breaches, or
- the refinancing gap opens.
- A driver explanation
- what caused the break (income, cost, capex, rate, timing, trapped cash).
- A playbook
- the smallest set of actions that restores resilience (pause capex, speed collections, refinance earlier, inject equity, restructure sweeps, etc.).
- A portfolio view and SPV/facility drill-down
Because risk usually breaks at SPV/facility level before it shows up in a blended portfolio average.
Scenario 1: Interest rates up + hedge roll-off
Definition
Stress the portfolio for a rate shock plus the realistic risk that hedges expire or coverage drops.
Typical stress levers
- +100 bps and +200 bps on floating base rates
- hedge expiry at maturity date (or partial coverage)
- refinancing margin +50-150 bps (if refi is within 12-24 months)
Common mistakes
-
Stressing rates but forgetting hedge maturities (the real cliff edge).
-
Applying the rate shock at portfolio level while covenants are tested at facility/SPV level.
-
Looking only at interest expense and missing the impact on:
- DSCR/ICR headroom
- cash runway
- distribution capacity
- refinancing affordability
Best-practice reporting
Include, by facility and portfolio:
- Weighted average cost of debt (base + margin)
- % floating after hedging
- DSCR/ICR headroom under Base / Downside / Severe
- "First breach date" (if any)
- Cash impact: annual interest cost delta and the month cash trough worsens
Decision triggers
- Any facility that moves inside a predefined headroom buffer (e.g., <0.20x cover headroom)
- Hedge maturities inside the next 12-18 months without an action plan
- Severe case requiring distributions to stop or capex to pause
Scenario 2: Occupancy down + collections slip
Definition
Stress revenue the way it actually breaks in real life: not just vacancy, but also collection timing and arrears.
Typical stress levers
- Physical occupancy down 2-5% (or a specific asset shock)
- Economic occupancy down due to incentives/rent-free on reletting
- Collections rate down (e.g., from 99% -> 97% or 95%)
- Bad debt / write-off assumption increase for a concentrated tenant exposure
Common mistakes
- Using month-end occupancy instead of average (day-weighted) occupancy for revenue impact.
- Stressing "rent" but ignoring arrears aging (which is what turns a revenue problem into a cash crisis).
- Applying a uniform vacancy assumption across assets instead of concentrating the shock where the risk actually sits (one asset, one tenant, one submarket).
Best-practice reporting
Show three layers (portfolio + worst SPVs/assets):
- Physical occupancy, leased occupancy, and economic occupancy
- Collections rate + arrears aging (0-30 / 31-60 / 61-90 / 90+)
- NOI impact and cash impact separately (NOI can look "fine" while cash deteriorates)
Decision triggers
- Any SPV projected to drop below minimum cash buffer due to collections timing
- Any asset with arrears >X% of monthly rent for 2 quarters
- Concentration: top tenant(s) represent >Y% of rent with weakening credit signals
Scenario 3: Non-recoverable OpEx shock
Definition
Stress costs that are hard to avoid and not fully recoverable: insurance spikes, utilities exposure, compliance spend, repairs, and contract inflation.
Typical stress levers
- +10-20% on insurance and key service contracts
- Utilities cost shock (especially if partially landlord-borne)
- Repairs and maintenance spike (e.g., reactive spend after a bad winter)
- Service charge recovery shortfall (where applicable)
Common mistakes
-
Stressing total OpEx without separating recoverable vs non-recoverable costs.
-
Letting "one-off" classification hide recurring cost pressure (if the "one-off" repeats every quarter, it is not a one-off).
-
Looking at NOI only and missing the knock-on impacts:
- debt service coverage
- capex deferral temptation
- tenant affordability and arrears risk
Best-practice reporting
Report:
- NOI margin and controllable OpEx ratio
- A simple "cost bridge" that shows which 2-3 lines drive most of the downside
- DSCR/ICR headroom sensitivity to cost inflation (because lenders do not care whether a cost was "unexpected")
Decision triggers
- Any asset where cost increases push NOI below a covenant buffer
- Any recurring "one-off" line that appears in 2+ quarters
- Any contract renewal that materially changes the cost base with no mitigation plan
Scenario 4: Refurb programme slips: downtime longer + capex higher
Definition
Stress capex the way it hurts: cash out sooner, downtime lasts longer, lease-up takes longer, and uplift arrives later.
Typical stress levers
- Capex +10-15% (plus contingency draw)
- Timing pull-forward (cash spends 1-2 months earlier than planned)
- Downtime +2-6 weeks, lease-up +1 month
- Incentives higher than expected (rent-free/leasing fees)
Common mistakes
- Treating refurb as only a capex line item (ignoring temporary NOI dip).
- Stressing total capex but ignoring the cash draw curve (the trough is the risk).
- Measuring payback using "headline rent uplift" instead of incremental NOI after incentives and downtime.
Best-practice reporting
A refurb stress test should output:
-
Monthly NOI dip + recovery (a ramp, not a step change)
-
Cash trough depth and timing (by SPV and portfolio)
-
Committed vs uncommitted capex (what is still optional)
-
Payback under Base / Downside / Severe, expressed as:
- cash payback month (first month cumulative incremental operating cash flow is at least cumulative capex)
- stabilised incremental NOI
Decision triggers
- Any refurb programme that pushes an SPV inside covenant buffers
- Any programme with a cash trough that requires upstream funding that may be restricted
- Any uplift assumptions that require "perfect lease-up" to break even
Scenario 5: Refinance squeeze: values down + spreads up + liquidity constraints
Definition
This is the scenario CFOs regret not running early enough: a combination shock where valuations soften, refinance pricing worsens, and liquidity gets constrained (including trapped cash in SPVs).
Typical stress levers
- Asset values down 5-15% (or cap rate expansion)
- Refinance margin +100-200 bps
- Amortisation requirements tighten
- Ability to upstream cash constrained (covenants, sweeps, reserve requirements)
- Disposal proceeds delayed (optional add-on if a sale is part of the plan)
Common mistakes
- Stressing valuation but forgetting that refinance terms change too (LTV tests plus affordability).
- Using "net debt" based on total cash without separating restricted/trapped cash.
- Reporting portfolio LTV only, when refinance risk sits in specific facilities with specific maturity dates.
Best-practice reporting
Build one page that leadership can read in two minutes:
- Maturity wall (next 6/12/24 months)
- LTV and headroom by facility (with valuation date clearly labeled)
- Refinance affordability: DSCR under refi pricing assumptions
- Liquidity reality: unrestricted vs restricted vs trapped cash, and where it sits
- Equity gap (if any): "How much cash/equity is required to refinance under the downside?"
Decision triggers
- Any maturity inside 12-18 months without a refi path under downside pricing
- Any facility where downside implies an equity gap
- Any portfolio that is "cash-rich" but cannot mobilise liquidity across SPVs
How to run these scenarios without building a monster model
The scalable way to do this quarterly is:
- Start with a base case you already trust
- latest actuals and a rolling forecast (even if simple)
- Use a small set of controllable levers
- rates, occupancy/collections, non-recoverable costs, capex/downtime, valuation/refi terms
- Measure outcomes consistently
- cash runway and cash trough
- DSCR/ICR headroom
- LTV headroom (with valuation date disclosed)
- breach timing ("first breach date")
- required actions and owners
- Run it at SPV/facility level, then roll up
Because average performance can hide concentrated risk.
This is where having a consolidated portfolio layer pays off: one-stop visibility across SPVs, standardised mappings so roll-ups are consistent, and "what if?" scenario planning that connects assumptions to cash flow and returns.
A simple quarterly stress testing checklist
If you want a repeatable quarterly ritual, here is a lightweight checklist:
-
Refresh debt schedule (balances, maturities, hedges, covenants)
-
Refresh capex commitments (spent vs committed vs discretionary)
-
Update occupancy + arrears snapshot
-
Update base forecast (next 12 months + 13-week cash)
-
Run the five scenarios above (Base / Downside / Severe)
-
Publish a 1-2 page stress test summary:
- "Top 3 vulnerabilities"
- "First breach dates (if any)"
- "Actions agreed this quarter"
Closing thought: stress tests are a leadership tool, not a finance artifact
The best CFO stress tests do not just say "here is the downside." They answer:
- Where do we break first?
- How much time do we have?
- What decisions restore resilience fastest?
Run these five scenarios quarterly and you will spend less time reacting to surprises--and more time steering the portfolio with confidence.
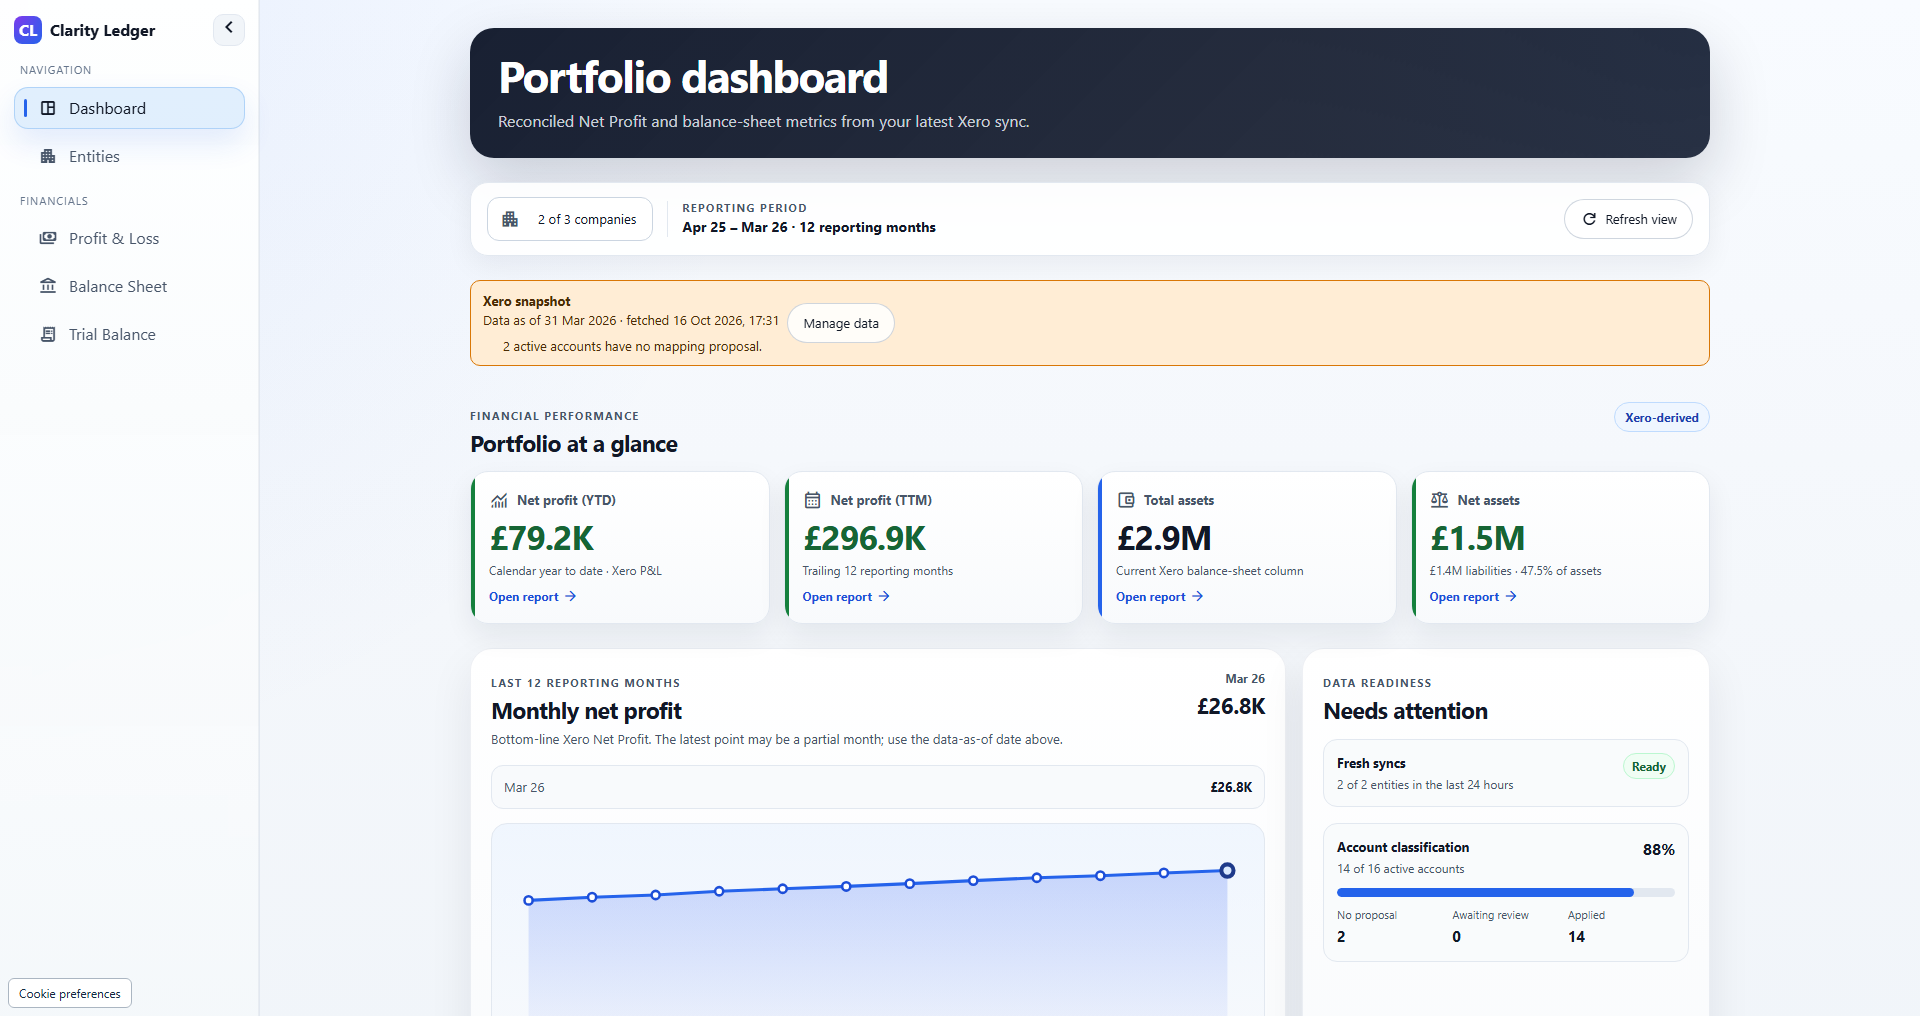
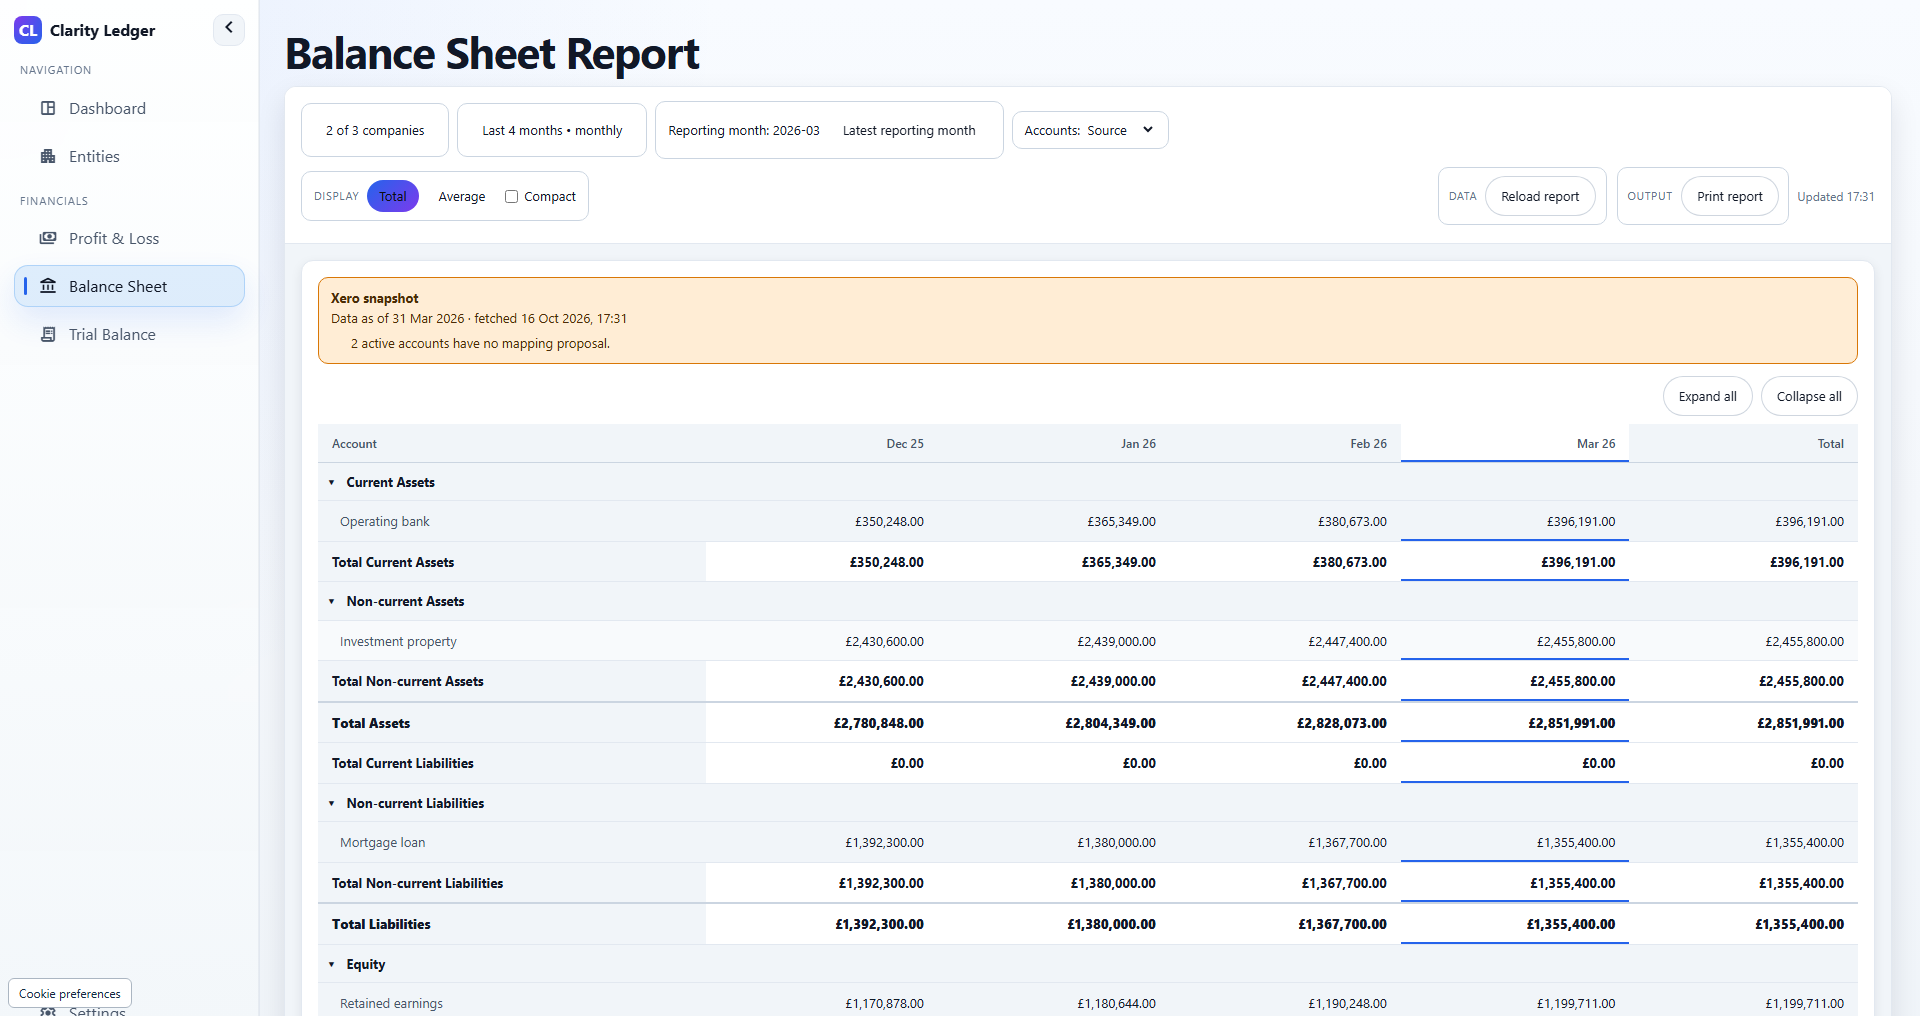
Reconcile the historical inputs to the same reporting periods before running your separate model. Review the current Clarity Ledger reporting workflow for selected GBP Xero companies; add stress assumptions, covenant definitions and management actions outside the app.
More operations insights for real estate finance teams.
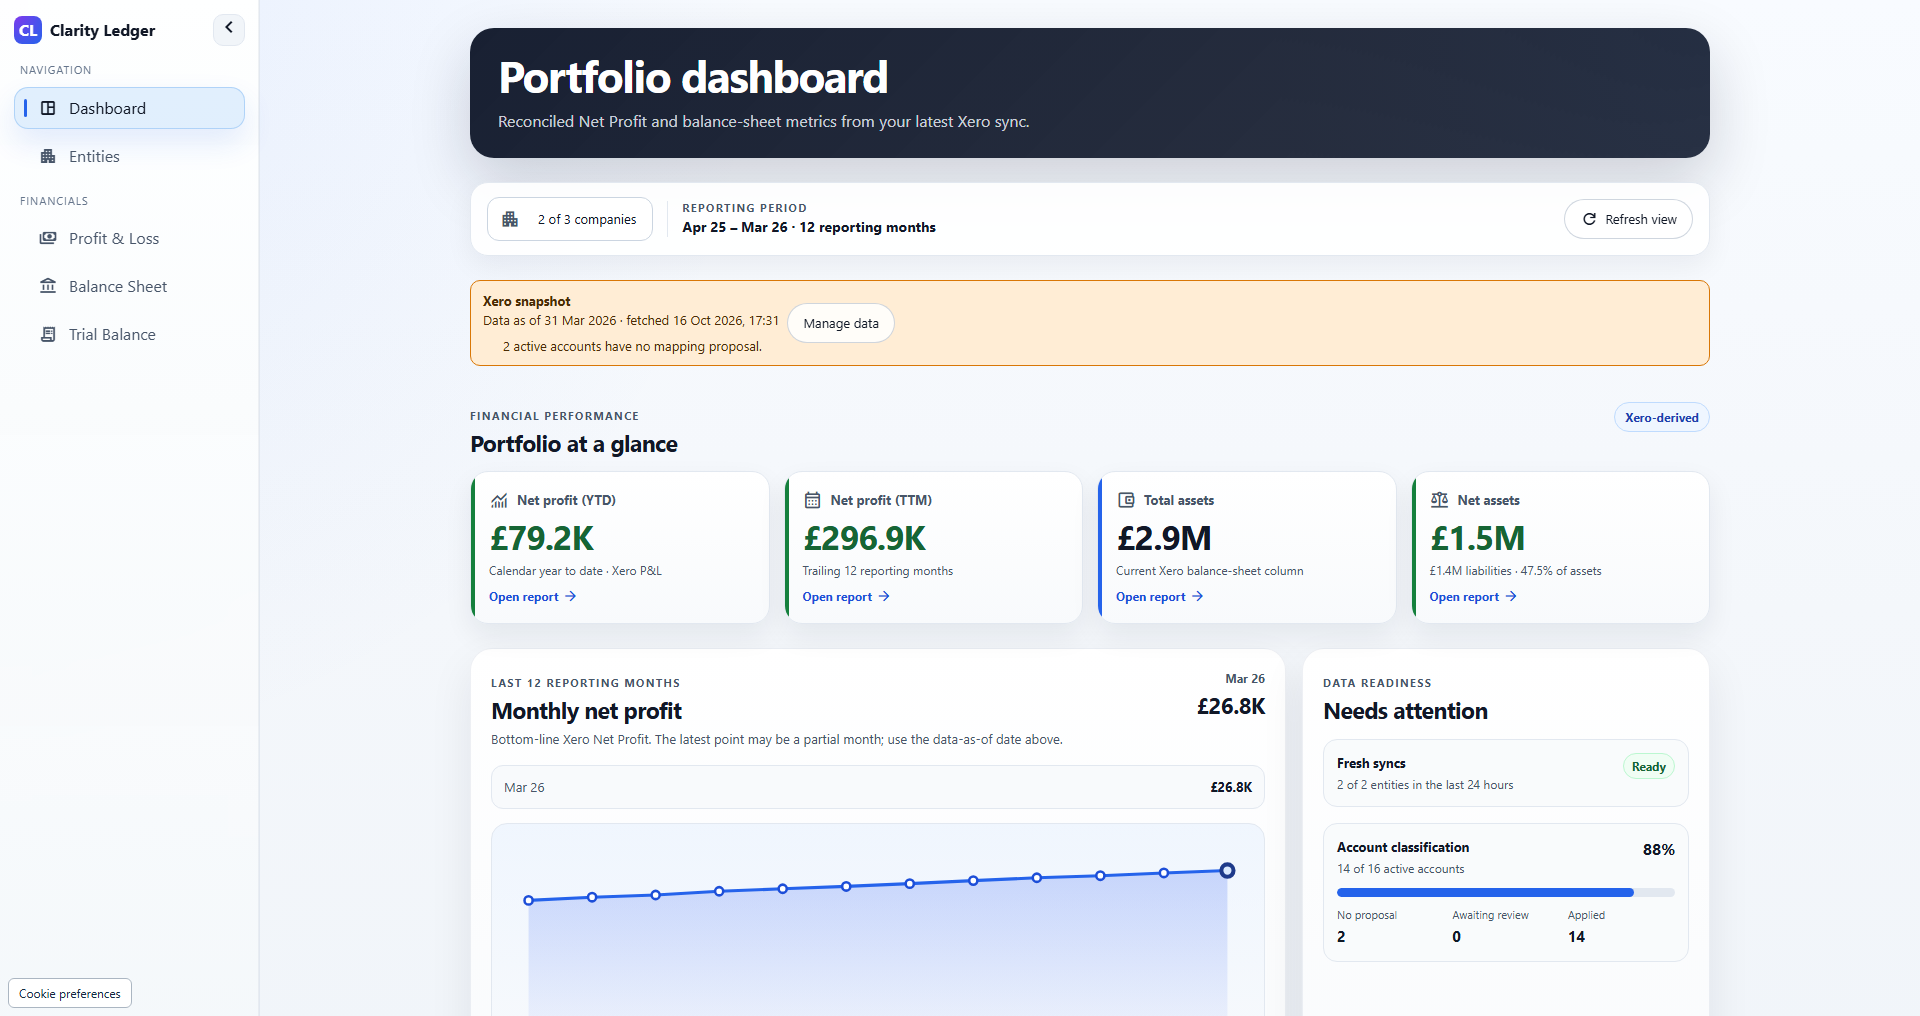
Actual Clarity Ledger portfolio dashboard · Illustrative demo data
Release notes that matter: what changed and why it helps finance teams
A finance-grade release note template that answers what changed, who is affected, why it matters, what to do, and how to validate-so multi-entity teams keep reconciliations, definitions, and trust intact.
Actual Clarity Ledger portfolio dashboard · Illustrative demo data
From raw accounting data to investor KPIs: a manual reporting framework
A manual investor KPI framework: align SPV inputs, document mappings and roll-up rules, calculate metrics separately, and reconcile outputs to evidence.
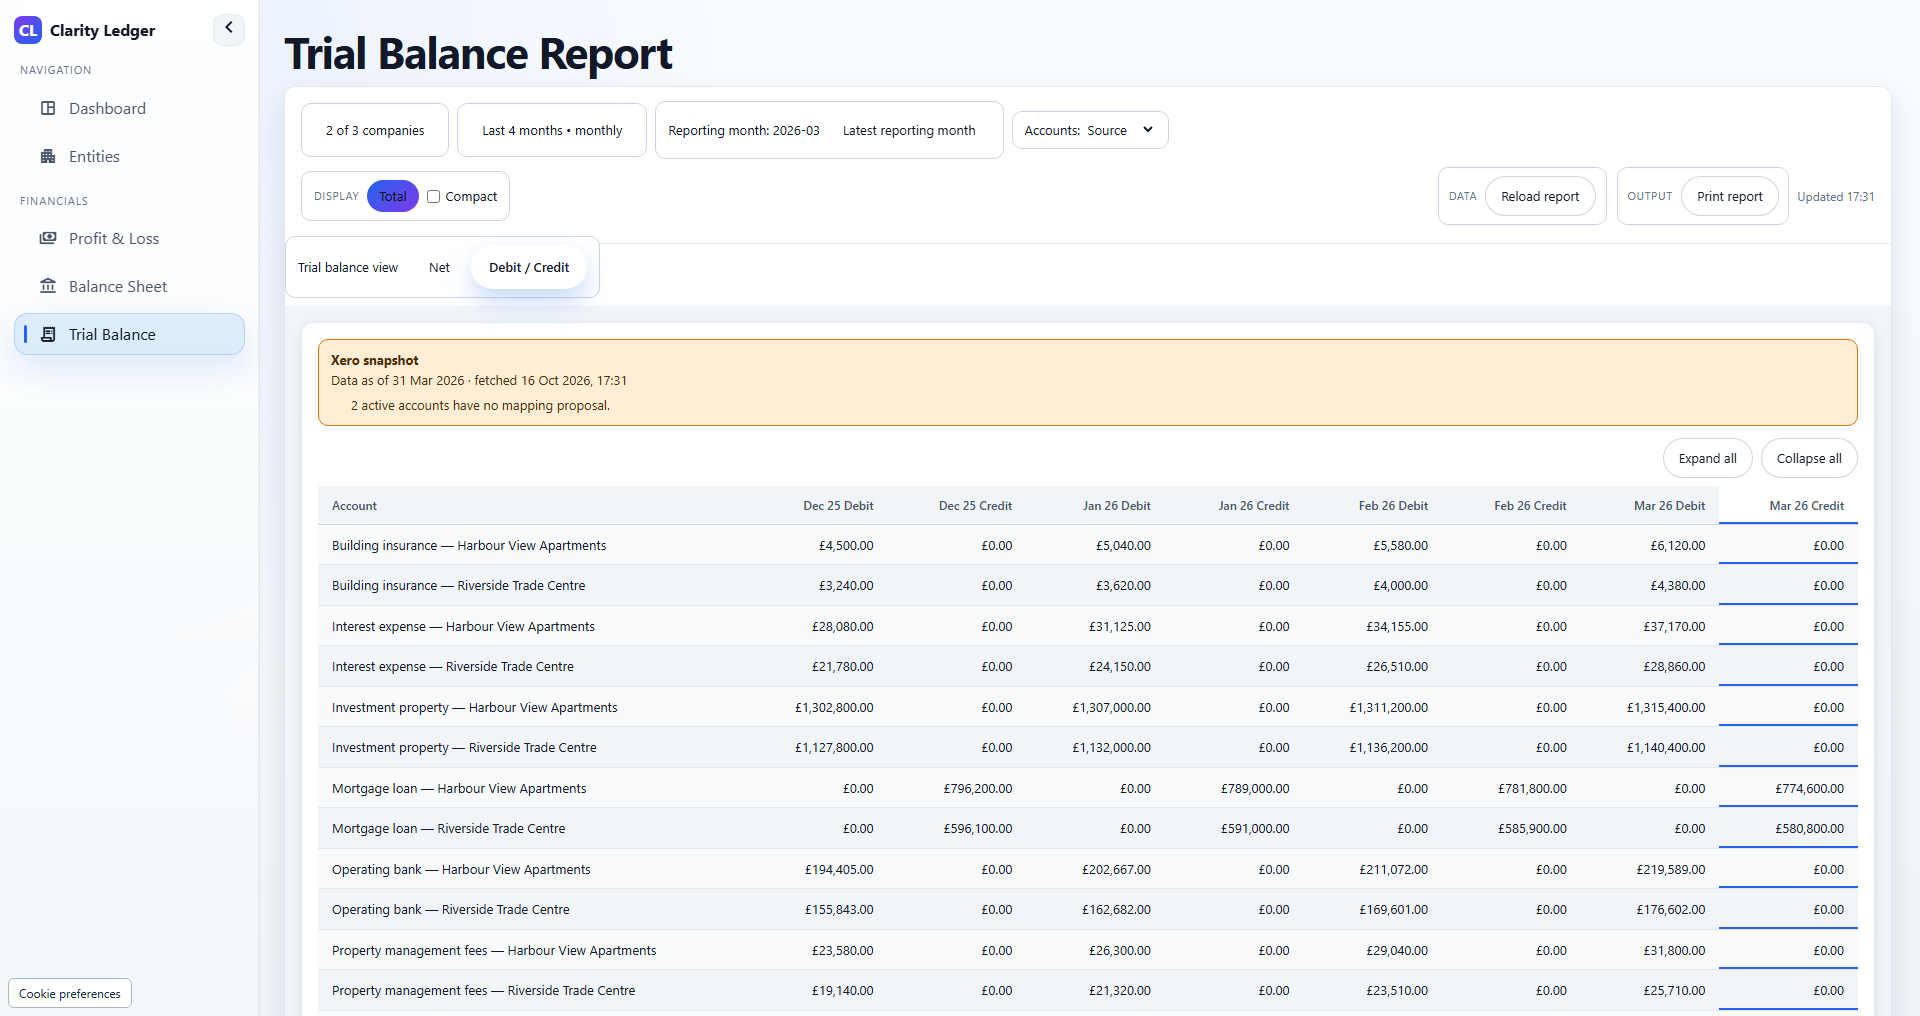
Actual Clarity Ledger trial balance report · Illustrative demo data
A month-end close checklist for property SPVs
Practical, evidence-based close routine for rent-led SPVs-cash, rent roll tie-outs, service charge, capex vs opex, debt and covenants-plus a downloadable PDF checklist you can use this month.
Ready for portfolio-grade reporting?
Review Xero, QuickBooks Online and FreeAgent companies in one dashboard, with saved financial reports and account mappings you apply. A 21-day trial is available once per eligible portfolio.