From scenario to action: turning model outputs into an investor narrative
Translate Base/Downside/Upside into a story investors trust and a plan the team can execute: cash, covenants, distributions, actions, and triggers.
Integration update, 20 October 2026: Clarity Ledger now connects Xero, QuickBooks Online and FreeAgent. GBP Xero examples below remain valid. Check current provider and currency eligibility; planning, KPI and pack-preparation tasks described as manual remain separate workflows.
The scenario models and investor narrative in this guide are prepared outside Clarity Ledger. Its current offer covers historical GBP Xero reports and reviewed mappings, without scenario planning or automated commentary.
How to translate "Base / Downside / Upside" into a clear story investors trust--and decisions your team can actually execute.
Most real estate teams can build scenarios.
The hard part is what happens next.
You run the model, you get 40 tabs of outputs, and then you are left with a familiar gap:
- Investors ask, "So what does this mean for cash and distributions?"
- The board asks, "What are you doing about it--and when?"
- Your team asks, "Which levers are we actually pulling next week?"
A scenario is just an answer key. An investor narrative is how you turn that answer key into confidence, alignment, and action.
This post shows a practical framework to go from scenario outputs -> investor-ready story -> operational plan, without drowning people in spreadsheets.
Why scenario outputs rarely land with investors
The problem is not the maths. It is translation.
Models naturally produce:
- IRRs, NPVs, waterfalls
- monthly cashflows
- dozens of sensitivities
- charts that are "technically correct"
Investors (and boards) are usually listening for:
- What changed since last update?
- What does this do to cash, covenants, and returns?
- What is within your control vs outside your control?
- What are you doing now, and what decisions do you need?
- What are the triggers and risks?
If your pack answers those in plain English, you are ahead of most reporting.
The narrative structure that works almost every time
Use this sequence:
1) Headline (one sentence)
"We remain on plan in Base Case; Downside is manageable with defined mitigations; liquidity remains our primary focus over the next 2 quarters."
2) What changed (facts, not vibes)
- Rates moved / refinance timing shifted
- Occupancy changed (and why: voids, downtime, demand)
- Capex timing changed (committed vs planned)
- Material one-offs (tax, insurance, compliance)
3) So what (impact on the 3 investor outcomes)
Investors care most about:
- Cash runway (minimum cash, when, and where)
- Covenants / constraints (DSCR/ICR/LTV, cash traps, reserves)
- Returns and distributions timing (not just IRR)
4) Now what (actions + owners + timing)
- Specific actions you are taking
- What you are not doing (and why)
- Timeline and milestones
5) Decision points + triggers (the governance layer)
- "If X happens, we do Y."
- "We will return to investors for approval if Z occurs."
This structure forces the model to serve a story--and the story to drive decisions.
Step-by-step: how to convert scenario outputs into narrative
Here is a repeatable workflow you can run monthly or quarterly.
Step 1: Pick the decision the narrative needs to support
A scenario pack is most credible when it is anchored to a real decision, like:
- Proceed / pause a refurb programme
- Rephase capex to protect liquidity
- Fix/hedge a portion of floating-rate exposure
- Negotiate covenant amendments early
- Adjust leasing strategy (price vs occupancy vs incentives)
If you cannot name the decision, you will default to sharing outputs without purpose.
Step 2: Run fewer scenarios--but make them decision-grade
Three scenarios is usually enough:
- Base Case: "What we believe will happen"
- Downside Case: "A plausible stress we can manage"
- Severe Case (optional): "A tail case for contingency planning"
Make sure each scenario has:
- start date
- ramp timing (not everything happens instantly)
- specific drivers (rates, occupancy, refurb cadence, refinance slip)
Investors trust scenarios that feel operational, not theoretical.
Step 3: Reduce the outputs to the "Big 5" story metrics
You can still compute everything--but your narrative should centre on:
- Minimum cash (and which SPV/asset hits it)
- Peak funding requirement (if cash goes negative)
- Covenant headroom (min DSCR/ICR/LTV proxy + breach months)
- NOI / earnings impact (monthly run-rate and full-year)
- Distribution timing (delay or reduction vs prior expectation)
If you put these five on one page, most investor questions get answered before they are asked.
Step 4: Build a simple "bridge" from Base -> Downside
A bridge is narrative gold because it explains why the downside moves.
Example bridge (illustrative categories):
- Occupancy/voids: £X reduction in NOI
- Collections/arrears: £Y reduction in cash receipts
- Higher rates: £Z increase in interest cost, reducing cash after interest
- Capex pull-forward: £A of cash outflow brought forward
- Mitigations (already in motion): £B improvement in cash
It turns "Downside is worse" into "Downside is worse because of these levers."
Step 5: Translate the bridge into actions (the part most packs skip)
For each negative driver, write:
- Action (what we will do)
- Owner (who is accountable)
- Timing (when it changes cash)
- Expected impact (which metric moves)
Example:
-
Driver: higher rates increase monthly interest by £X
- Action: hedge 50% exposure / refinance earlier / reduce drawings
- Owner: CFO / Debt advisor
- Timing: next 30-60 days
- Impact: improves minimum cash by £Y; improves DSCR headroom by Z ratio points
Investors do not just want awareness. They want control.
The investor narrative template you can copy/paste
Below is a "one-page narrative" structure that works well in investor updates.
Portfolio update (period ending: ___)
Headline:
Base Case remains achievable; Downside Case delays distributions by ___ months. Liquidity remains the key focus through ___.
What changed this period (facts):
- Occupancy: __% -> __% driven by ___
- Rent: passing rent up/down due to ___
- Debt: all-in rate now ___%; refinance timing assumption moved to ___
- Capex: ___% of annual plan committed; phasing shifted due to ___
Scenario summary (So what):
- Base Case: minimum cash £___ in month ___; covenant headroom remains ___
- Downside (-5pp occ / +150bps / capex slip): minimum cash £___ in month ___; DSCR lowest ___ in month ___
- Mitigated Downside (actions applied): minimum cash improves to £___; DSCR buffer restored to ___
Enter the actual sign of each minimum cash balance; the template does not assume that it is negative.
Actions (Now what):
- Leasing: ___ (owner ___, by ___)
- Capex rephase: ___ (owner ___, by ___)
- Debt/covenants: ___ (owner ___, by ___)
Decision points / asks:
- Approve capex rephase / contingency budget of £___
- Confirm hedge approach / refinance mandate by ___
- Governance trigger: if occupancy < __% for __ months, pause refurb starts
Risks to watch:
- ___ (leading indicator: ___)
- ___ (leading indicator: ___)
That is a narrative investors can read quickly, understand, and act on.
Example language that makes scenarios feel real
If you want your scenario pack to sound credible (not alarmist), these phrases help:
- "Downside is driven primarily by timing, not total value."
- "The stress is concentrated in SPV ___, driven by ___."
- "We have three levers available within 60 days: ___."
- "Our priority is protecting minimum cash through ___; returns are second-order in the next quarter."
- "We are front-running covenant risk by ___ rather than waiting for a breach."
Common mistakes that break trust
Mistake 1: Leading with IRR instead of liquidity
IRR is important, but cash and covenants determine survival and optionality. Start there.
Mistake 2: Too many scenarios, too little insight
If you show 12 scenarios, you will get 12 debates. Show 2-3 that map to decisions.
Mistake 3: No link from outputs to actions
A scenario that does not change behaviour is just an academic exercise.
Mistake 4: "Portfolio numbers" with no drill-down
If an investor asks "which assets drove this?" and you cannot answer quickly, confidence drops.
Mistake 5: Hidden definition changes
If NOI, capex, or "operating expenses" subtly change definition month-to-month, your narrative becomes untrustworthy. Consistency beats cleverness.
What "scenario-to-action" looks like at scale across SPVs
In multi-SPV portfolios, the hardest part is not modelling one asset--it is keeping the portfolio story consistent and reconcilable:
- consistent rollups across entities
- standardised charts of accounts and mappings
- outputs that drill from portfolio -> SPV -> account
- repeatable commentary prepared and approved by the finance team
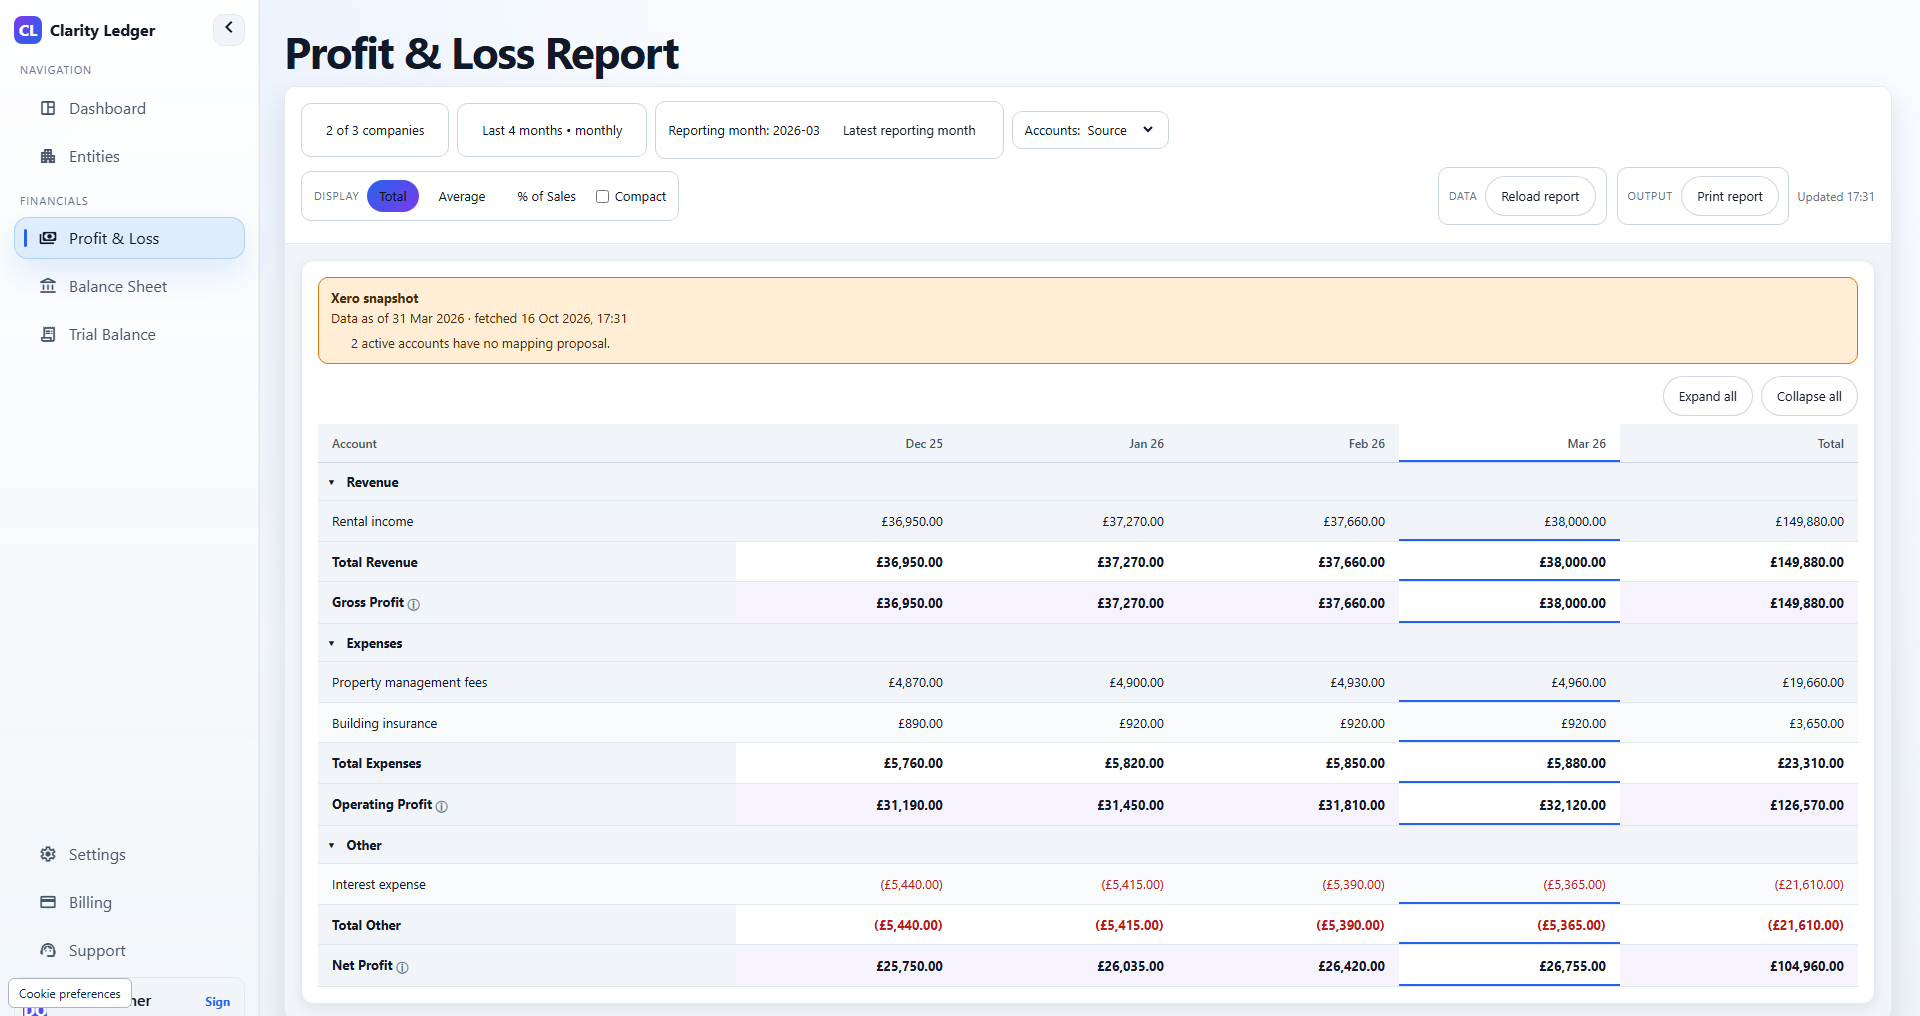
Clarity Ledger supports the historical reporting foundation for selected GBP Xero companies: saved profit and loss, balance sheet and trial balance reports, with mappings you review and apply. Add scenario assumptions, cash and return calculations, commentary and investor-pack approvals through your separate finance workflow.
See the current reporting scope. Forecasts, scenarios and automatic investor packs are not included.
More operations insights for real estate finance teams.
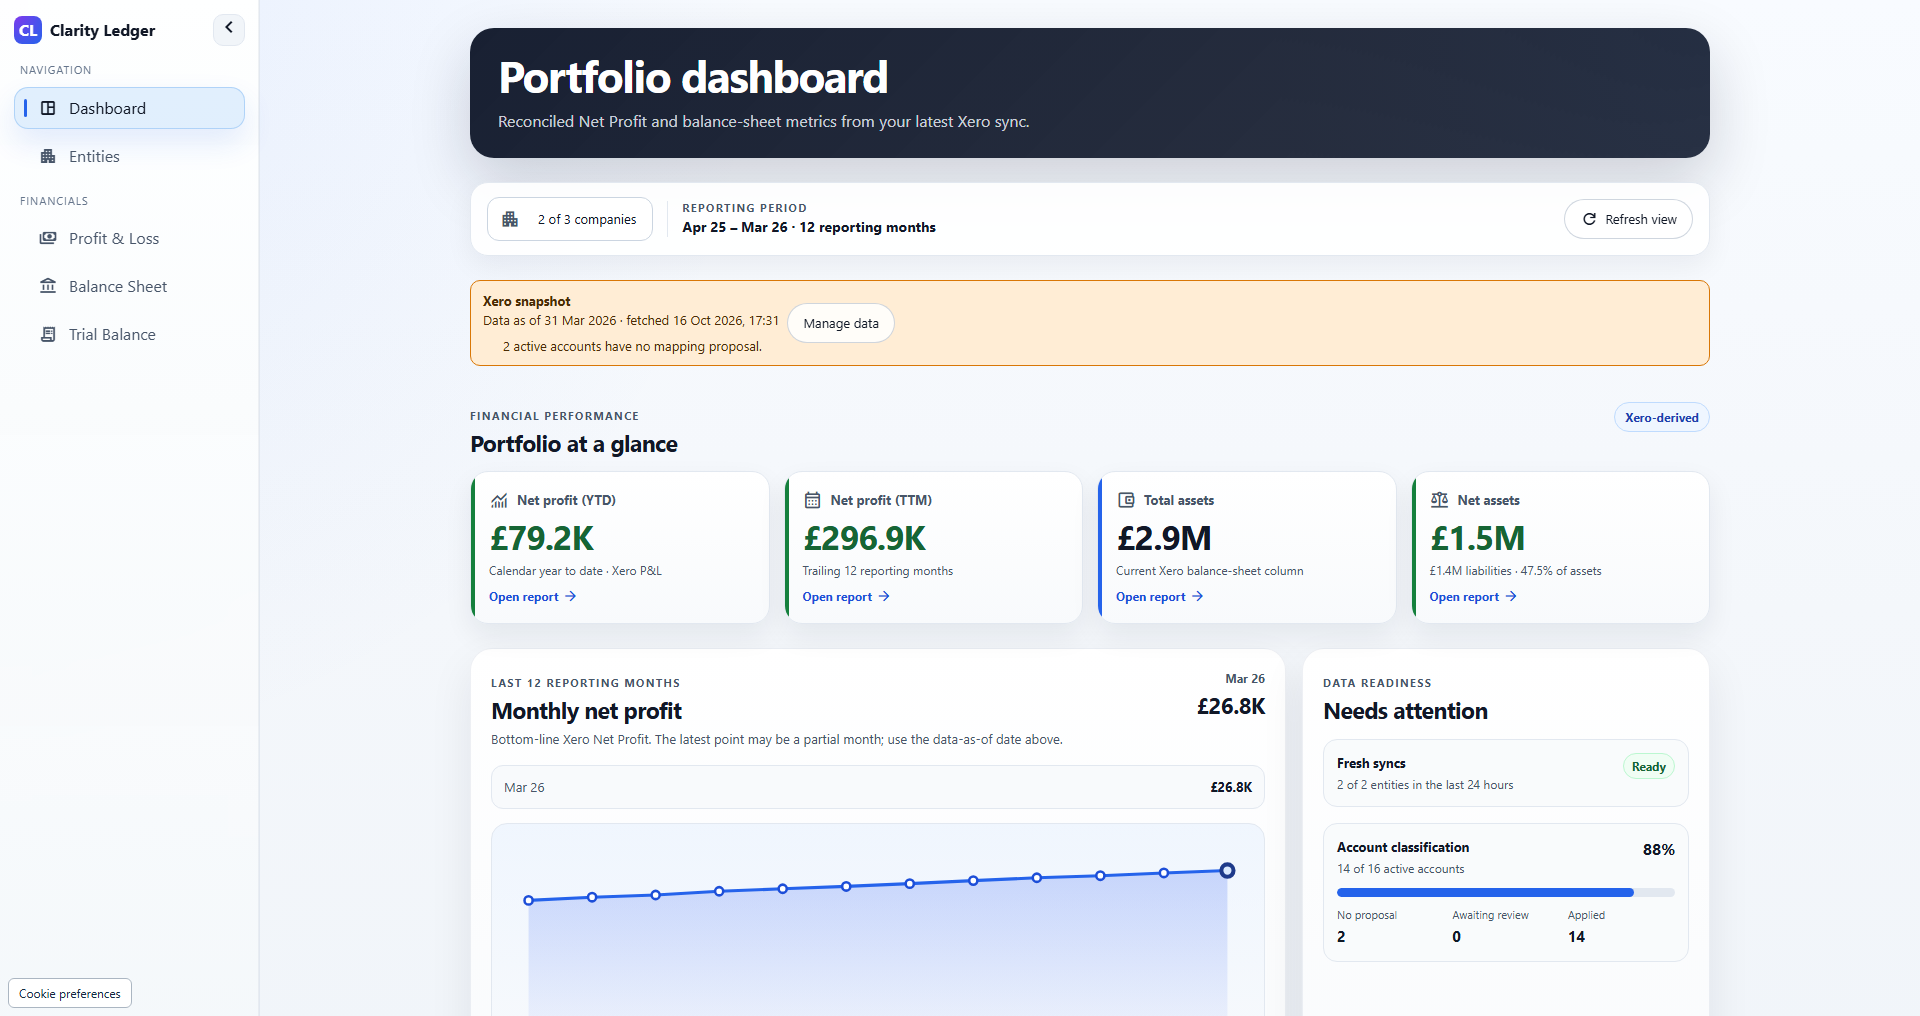
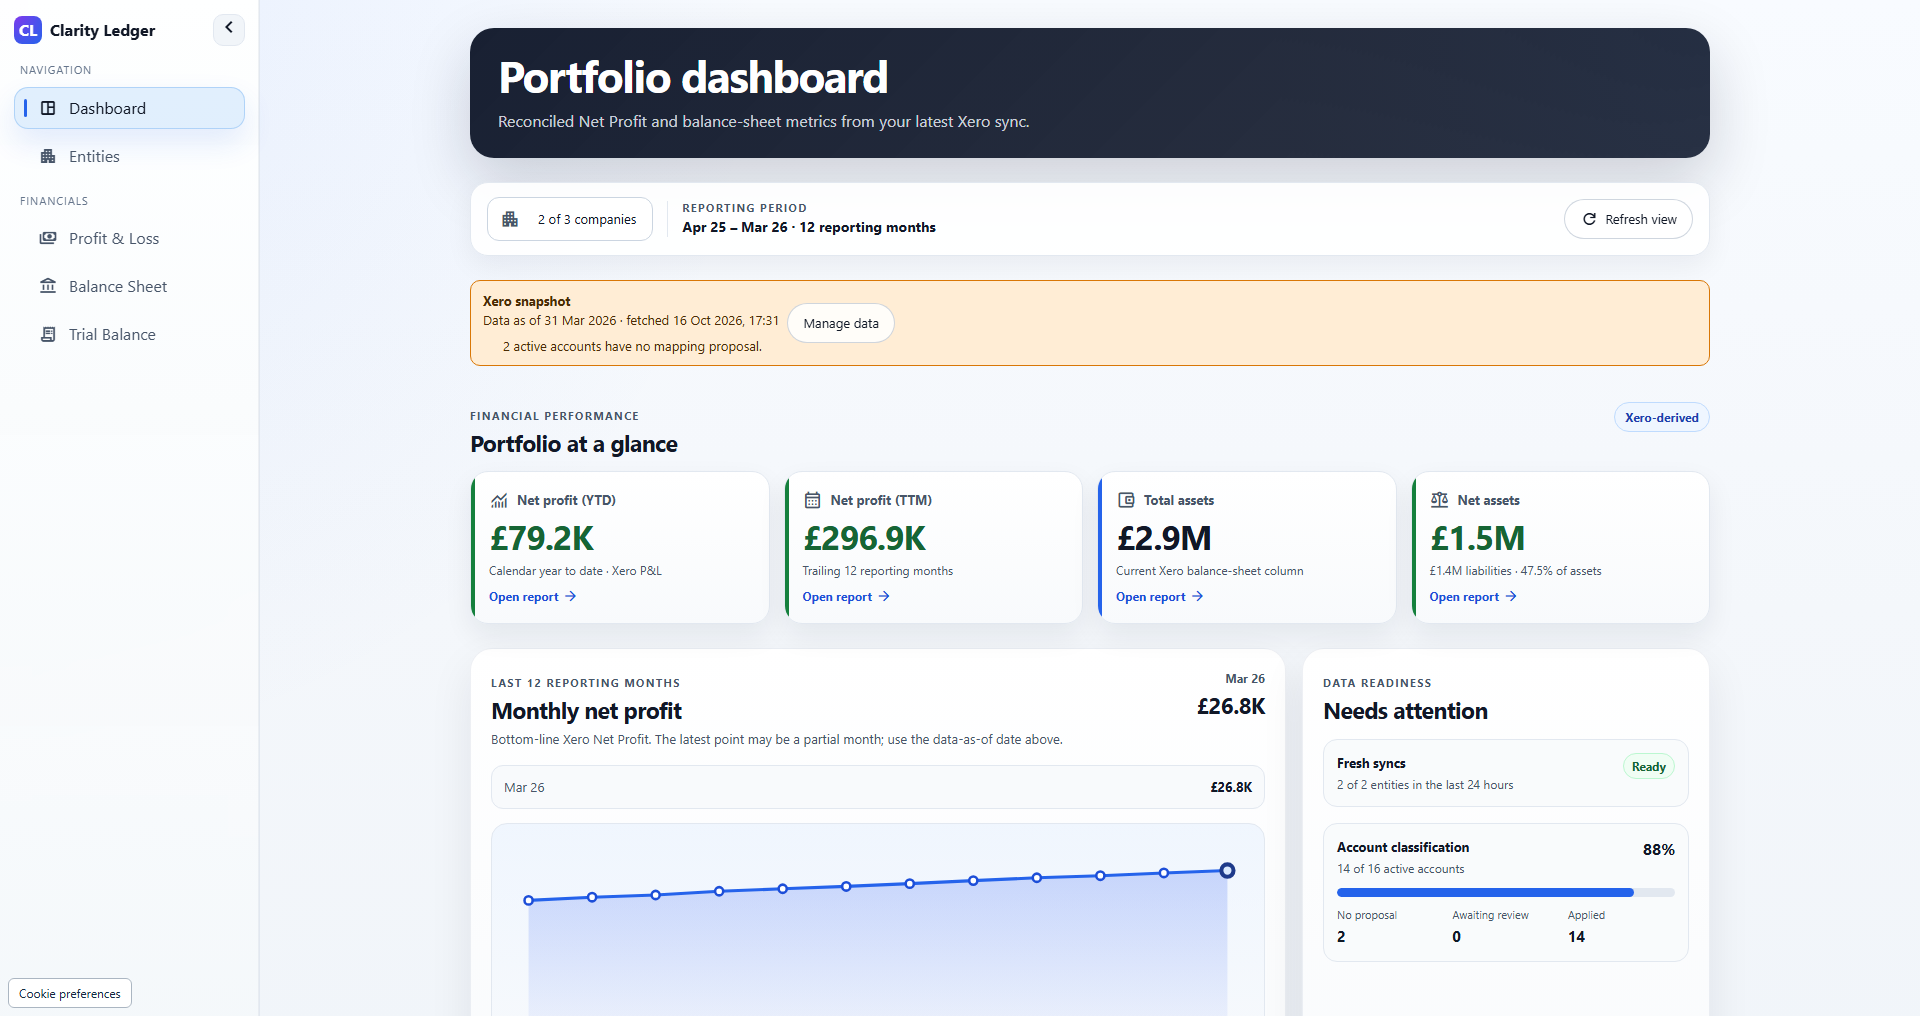
Actual Clarity Ledger portfolio dashboard · Illustrative demo data
Release notes that matter: what changed and why it helps finance teams
A finance-grade release note template that answers what changed, who is affected, why it matters, what to do, and how to validate-so multi-entity teams keep reconciliations, definitions, and trust intact.
Actual Clarity Ledger portfolio dashboard · Illustrative demo data
From raw accounting data to investor KPIs: a manual reporting framework
A manual investor KPI framework: align SPV inputs, document mappings and roll-up rules, calculate metrics separately, and reconcile outputs to evidence.
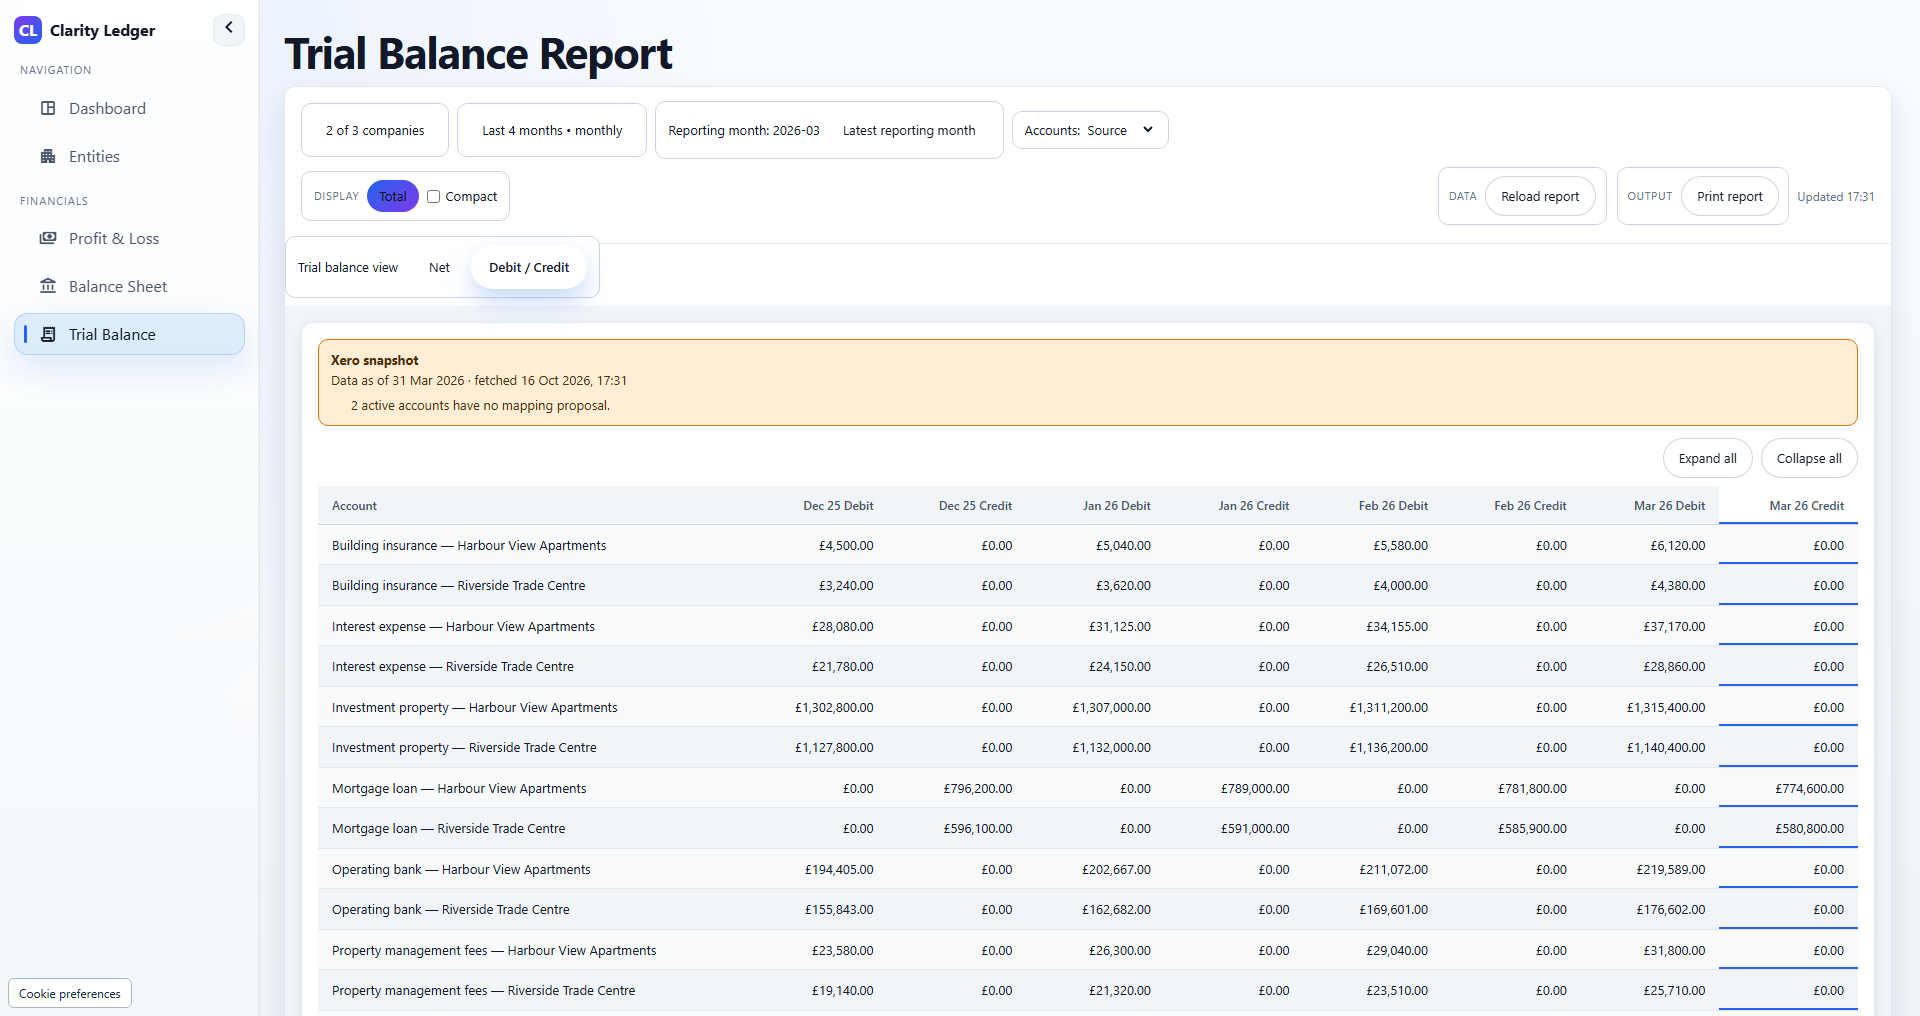
Actual Clarity Ledger trial balance report · Illustrative demo data
A month-end close checklist for property SPVs
Practical, evidence-based close routine for rent-led SPVs-cash, rent roll tie-outs, service charge, capex vs opex, debt and covenants-plus a downloadable PDF checklist you can use this month.
Ready for portfolio-grade reporting?
Review Xero, QuickBooks Online and FreeAgent companies in one dashboard, with saved financial reports and account mappings you apply. A 21-day trial is available once per eligible portfolio.