Cash-on-Cash Return vs IRR: Property Yield Explained
Compare cash-on-cash return, property yield and IRR: clear formulas, a worked example, and the cash-flow, debt and valuation differences behind each measure.
Cash-on-cash return compares annual pre-tax cash flow after debt service with the cash equity invested. IRR measures the money-weighted return across the investment's cash flows and their timing, including sale proceeds or an assumed ending value. Property yield answers a third question: annual net operating income (NOI) relative to property value or cost.
That is why cash yield and IRR can disagree without either calculation being wrong. A property can generate income while retaining cash instead of distributing it. An IRR estimate can change when the assumed exit value changes, even though no extra cash has been paid to investors.
| Measure | Basis used in this guide | Main question |
|---|---|---|
| Property yield | Annual NOI / stated property value or cost | What operating income does the asset produce? |
| Cash-on-cash return | Annual pre-tax cash flow after debt service / cash equity invested | What annual cash return does the investment generate on the cash invested? |
| Distributed cash yield | Period distributions / stated equity base | What cash did the investor actually receive for that period? |
| IRR | Discount rate giving all investor cash flows a net present value of zero | What return do the amounts and timing of those cash flows imply? |
State the reporting period, cash-flow definition and equity base. An unannualised monthly cash yield is not comparable with an annual property yield. Cash flow after debt service can differ from cash actually paid to investors because of reserves, capital spending or retained cash. In this article, distributed cash yield means cash actually paid; cash-on-cash return and cash available for distribution must be labelled separately.
The worked property example below compares yield, annual distributions and a five-year IRR using the same explicitly illustrative figures. The monthly reporting checklist then explains the dates, debt and reserves to check before comparing properties or SPVs.
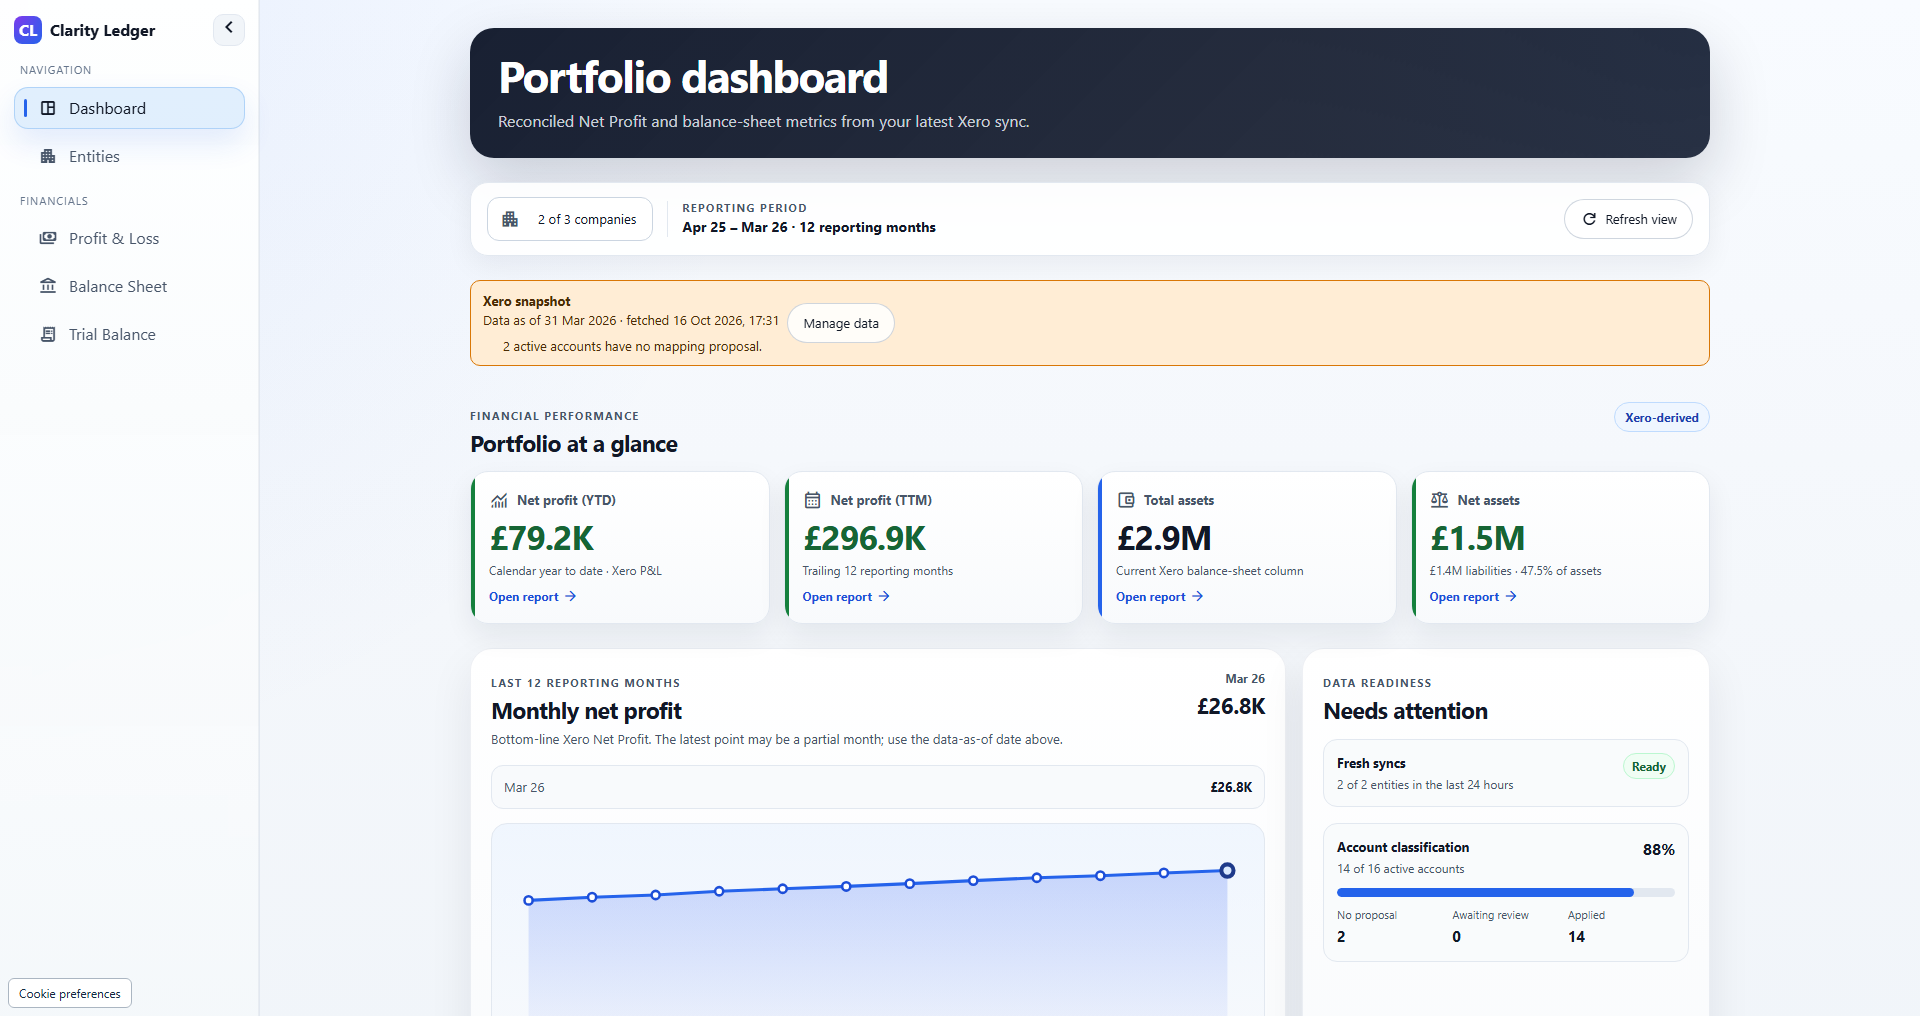
These are manual finance-team calculations. Clarity Ledger supplies historical profit and loss, balance sheets and trial balances after successful syncs, with account mappings you review. It supports Xero and QuickBooks Online companies in GBP, EUR or USD, and FreeAgent UK GBP limited companies. GBP management presentation requires covered, reviewed exchange rates. It does not calculate NOI, yields or IRR, maintain property valuations, forecast returns or generate investor packs.
The short version: what each metric is "for"
Yield
What it tells you: How hard the asset is working (unlevered operating return).
Best for: Comparing properties, pricing/valuation discussions, asset management.
Works well monthly? Yes-if you define NOI and the denominator consistently.
Cash yield
What it tells you: What the equity is actually receiving in cash (distributed cash yield).
Best for: Distribution-focused investors, liquidity planning, "are we paying out?"
Works well monthly? Yes-if you define "cash to equity" and the equity base consistently.
IRR
What it tells you: Total return over time, including timing and exit value.
Best for: Deal underwriting, manager performance across time, exit planning.
Works well monthly? Usually not as a "headline monthly KPI" (unless you are very clear about assumptions and valuation frequency).
Step 1: Define the metrics (in plain English)
1) Yield (often "cap rate" / "NOI yield")
In most property reporting, "yield" means an NOI-based yield:
Yield = Annual NOI / Property value
Where:
-
NOI is your chosen Net Operating Income definition (this needs to be standardised across SPVs).
-
Property value might be:
- latest independent valuation,
- internal valuation,
- or cost/purchase price (in which case you are reporting "yield on cost").
Why it is useful: it is primarily an asset-level measure. It answers:
"Given the asset's value, what operating income is it producing?"
Common "yield" variants you will see (and should label explicitly):
- In-place yield: based on current/actual NOI (often trailing 12 months or run-rate).
- Stabilised yield: based on expected NOI once leasing/ops stabilise.
- Yield on cost: annual NOI / total cost (purchase + capex), useful for measuring execution vs underwriting.
Monthly reporting tip: If you publish yield monthly, specify:
- whether NOI is monthly annualised, run-rate, or TTM (trailing 12 months), and
- what value you are using (and the "as of" date).
2) Cash-on-cash return and distributed cash yield
Cash-on-cash return is commonly calculated using annual pre-tax cash flow after debt service divided by cash equity invested (CFA Institute's commercial real estate overview). It does not include an unrealised property-value gain as current cash income. State how capital spending, reserves and the equity base are treated in your calculation.
The distributed cash yield used in this guide measures actual cash paid to equity investors:
Cash yield = Cash distributed to equity for the stated period / Equity invested
Label the period explicitly. For a simple annualised monthly cash yield, multiply the monthly distribution by 12 before dividing; this assumes the month is representative. Do not compare an unannualised monthly percentage with an annual property yield.
The challenge is that teams often disagree on both parts:
- What counts as "cash distributed"?
- What is the equity base (paid-in equity, average equity, net of return of capital, etc.)?
A practical definition for monthly packs is:
- Cash available to equity (for the period) = operating cash flow after debt service and after any agreed reserves/capex holds minus/plus any working capital movements you treat as distributable. Record actual distributions separately; available cash can be retained.
- Equity base = total contributed equity (and be clear whether it is gross paid-in equity or net of returned capital).
Why it is useful: it answers:
"What cash return is the equity actually receiving?"
It is especially important in levered structures where an asset can have a modest property yield but a strong (or weak) cash yield depending on financing and distribution policy.
3) IRR (Internal Rate of Return)
IRR is a money-weighted measure of total return, reflecting the amounts and timing of cash flows (CFA Institute):
It is the discount rate that makes the present value of all equity cash flows (including the sale) equal to zero.
Why it is useful: it answers:
"Given the timing of cash flows and the exit outcome, what annualised return did equity earn?"
Why it can be problematic monthly: IRR is highly sensitive to:
- exit value assumptions,
- timing (one month earlier/later matters),
- and valuation updates (if you only revalue quarterly/annually, your "monthly IRR" is essentially stale, then jumps).
Step 2: Why monthly reporting makes these metrics go wrong
Here are the failure modes we see most often across multi-SPV portfolios:
1) NOI inconsistency (the root cause)
If one SPV includes certain costs above NOI and another pushes them below NOI, your yield comparisons are broken.
Fix: standardise NOI definitions and map each SPV's accounts into a portfolio reporting structure (so NOI is calculated consistently before you compute yields).
2) Denominator drift (valuation vs cost vs "last year's number")
A yield calculated on:
- purchase price,
- last year's valuation,
- or an updated appraisal
...can all be "correct," but they are not comparable unless labelled.
Fix: publish the denominator explicitly:
- "Yield (TTM NOI / Valuation as of 30 Sep 2025)"
- "Yield on cost (TTM NOI / Total cost to date)"
3) Annualising one month of NOI
If you annualise a single month's NOI (multiply by 12), seasonality and one-offs can distort yield.
Fix: prefer:
- TTM NOI (best for stability), or
- run-rate NOI (best for operational focus), with a clear definition.
4) Cash yield confusion: distributions vs cash flow
Some teams report cash yield using:
- distributions paid, while others use
- cash generated (even if retained in the SPV).
Both can be useful, but they mean different things.
Fix: choose one headline version and optionally show the other:
- Cash yield (distributed) and/or
- Cash yield (available)
5) "Monthly IRR" that is really just a guess
If the valuation does not update monthly, IRR is not truly being "measured" monthly-it is being assumed.
Fix: put IRR in the pack, but treat it as:
- Quarterly (or valuation-date) metric, and
- always show the valuation "as of" date and key assumptions.
Worked example (shows why the numbers differ)
Assume a property has:
- Value (or purchase price): 10,000,000
- Annual NOI: 600,000
- Debt: 6,000,000 at 4.5% interest
- Annual principal amortisation: 60,000
- Equity invested: 4,000,000
- Annual distributions: 240,000 (rest retained as reserves)
All monetary figures in this example are GBP. Assume five year-end principal repayments of £60,000, no redraws, and fixed year-end distributions. Retained reserves are excluded from the illustrative exit proceeds below; include any reserve release when calculating an actual investor return.
Yield (NOI yield)
Yield = 600,000 / 10,000,000
= 0.06 = 6%
Cash yield (distributed to equity)
Cash yield = 240,000 / 4,000,000
= 0.06 = 6%
So far, both are 6%-but they are not the same thing.
IRR (depends on timing + exit)
If the investment distributes 240,000 per year for 5 years, and sells in year 5 for 11,000,000 (net), with 5,700,000 of debt remaining after five £60,000 principal repayments, equity receives 5,300,000 from the sale.
Equity cash flows:
- Year 0: -4,000,000
- Years 1-4: +240,000
- Year 5: +240,000 + 5,300,000
That produces an annual IRR of about 11.2%, using year-end cash flows of -£4,000,000, £240,000, £240,000, £240,000, £240,000 and £5,540,000. Use actual cash-flow dates and all investor receipts for an actual return calculation.
Key point: IRR can be much higher (or lower) than yield/cash yield because it includes capital gain (or loss) and timing.
What belongs in a monthly report?
Here is a practical rule:
- If a metric is mostly driven by operations and accounting reality, it can be monthly.
- If a metric is mostly driven by valuation/exits/assumptions, treat it as quarterly or "as of valuation date."
Recommended monthly pack metrics (portfolio + property level)
| Metric | What it is for | Recommended frequency | Make it reliable by... |
|---|---|---|---|
| NOI (MTD / YTD / TTM) | Operating performance | Monthly | Standardise NOI definitions + mappings across SPVs |
| Yield (TTM NOI / latest value) | Asset efficiency & comparability | Monthly | Use TTM NOI + show valuation "as of" date |
| Yield on cost (TTM NOI / total cost) | Execution vs underwriting | Monthly | Track total cost-to-date consistently (incl. capex policy) |
| Cash yield (distributed) | Investor cash return | Monthly | Define "distribution" and equity base clearly |
| Cash yield (available) (optional) | Liquidity & distribution capacity | Monthly | Define reserves/debt service treatment |
| Occupancy + rent roll KPIs | Drivers of NOI | Monthly | Consistent definitions across properties |
| Gearing / leverage | Risk & capital structure | Monthly | Standard debt metrics + covenant tracking |
Where IRR fits
Include IRR, but do not make it the headline monthly KPI unless you can update valuations consistently.
Best practice in monthly packs:
- Show IRR "as of" the last valuation date (quarter-end or appraisal date).
- Include Realised vs Unrealised IRR (if applicable).
- Include a short "what changed" note when IRR moves (valuation update, refinancing, exit assumption change).
The cleanest approach: publish a "Return Metrics" page with clear labels
A strong monthly investor/board pack often separates:
Page A: Monthly operating performance (high confidence)
- NOI (MTD/YTD/TTM)
- Yield (TTM NOI / value, with date)
- Cash yield (distributed + optionally available)
- Occupancy + key drivers
- Exceptions / one-offs
Page B: Deal-level total return (assumption-sensitive)
- IRR (as of valuation date)
- Equity multiple (TVPI / MOIC, if you use it)
- Sensitivities (optional): exit value -5%, rates +100 bps, occupancy -3%
This structure prevents the classic confusion:
"Did performance improve, or did assumptions change?"
What to say (and not say) in the commentary
If you are writing monthly narrative, keep the messaging aligned with what each metric means:
- Yield moved -> usually means NOI changed, value changed, or your NOI basis changed.
- Cash yield moved -> usually means distributions changed, debt service changed, or reserves policy changed.
- IRR moved -> usually means valuation/exits/timing assumptions changed (or you had a major cash event).
This makes monthly commentary faster and more credible-especially if you are generating "what changed this month" style narratives on top of standardised portfolio data.
A simple decision framework for your team
If you have to choose what to emphasise in monthly reporting:
-
Lead with Yield + Cash Yield
They are understandable, operationally anchored, and useful month-to-month. -
Include IRR, but treat it as "valuation-date"
It is too assumption-sensitive to be the primary monthly KPI unless valuations update monthly. -
Standardise NOI first
Without consistent NOI and account mappings across SPVs, yield comparisons are noise.
More operations insights for real estate finance teams.
Actual Clarity Ledger portfolio dashboard · Illustrative demo data
Release notes that matter: what changed and why it helps finance teams
A finance-grade release note template that answers what changed, who is affected, why it matters, what to do, and how to validate-so multi-entity teams keep reconciliations, definitions, and trust intact.
Actual Clarity Ledger portfolio dashboard · Illustrative demo data
From raw accounting data to investor KPIs: a manual reporting framework
A manual investor KPI framework: align SPV inputs, document mappings and roll-up rules, calculate metrics separately, and reconcile outputs to evidence.
Actual Clarity Ledger trial balance report · Illustrative demo data
A month-end close checklist for property SPVs
Practical, evidence-based close routine for rent-led SPVs-cash, rent roll tie-outs, service charge, capex vs opex, debt and covenants-plus a downloadable PDF checklist you can use this month.
Ready for portfolio-grade reporting?
Review Xero, QuickBooks Online and FreeAgent companies in one dashboard, with saved financial reports and account mappings you apply. A 21-day trial is available once per eligible portfolio.